The Copper Chart Causing Alarm

The Copper Chart Causing Alarm

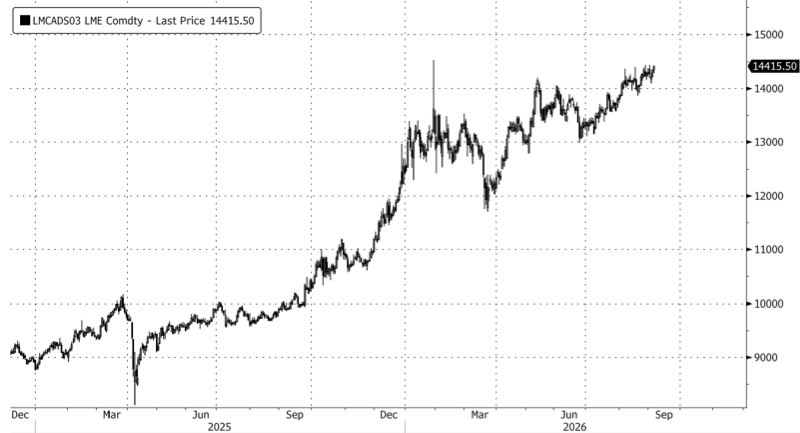
Copper futures in London continue to move higher, once again approaching record highs, as US buyers purchase record volumes from the seaborne market, with imports reaching 200,000 tons in July. A phased US tariff would keep that buying in motion for longer, further tightening the ex-US market and limiting any near-term price correction in London trading.

Rafael Barcellos, head of Latin American Metals & Mining and Pulp & Paper Equity Research at Bradesco BBI, wrote in a note last week that global mine supply is deteriorating. He warned that severe weather in Chile has forced Antofagasta and Lundin to cut their production guidance, further tightening an already stressed physical market.

Barcellos explained:

Copper prices extended their July rally into August, running above US$14,000/t throughout the month and reaching ~US$14,450/t as of August 30. Momentum has been driven by near-term physical tightness, as refined copper continues to flow into the US ahead of a potential import tariff.

While market consensus frames the policy as a binary outcome for copper — a tariff being supportive for prices and a no-tariff decision being negative — we would argue instead that both outcomes are ultimately bearish, and that it is the uncertainty around the tariffs that is intensifying the current upward momentum. Should tariffs not be implemented, the massive inventories accumulated in the US would be redirected elsewhere, increasing global supply availability. However, should the US instead move ahead, US buyers would likely reduce near-term procurement given the elevated stocks already built ahead of the decision, ultimately reducing regional demand and easing tightness elsewhere. That said, a phased tariff (e.g. an incremental rate over the coming years) — which we do see as the most likely scenario — should help keep US buyers in the seaborne market for longer, smoothing rather than removing the demand adjustment and limiting the near-term downside to prices.

On the supply side, the concentrate market remains tight, further exacerbated by extreme weather in Chile, which led Antofagasta and Lundin Mining to lower their 2026 production guidance ranges to 625-655kt (from 650-700kt) and 300-325kt (from 310-335kt), respectively, reflecting disruptions at Los Pelambres and Caserones. On the refined side, amid persistent concentrate tightness, Chinese smelters have increasingly turned to secondary feedstock, with copper scrap imports rising +15% YoY in July (+9% YTD)

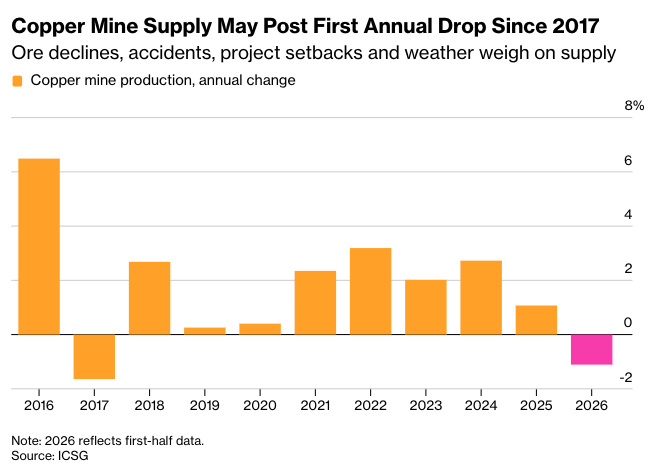
Barcellos’ view of the copper market was echoed in a Bloomberg report on Friday, which cited International Copper Study Group data showing that global mine production fell 1.1% during the first half of 2026, with output at industry giants Codelco and Freeport-McMoRan declining by double digits.

Separately, Morgan Stanley, which began the year forecasting supply growth, now expects mine production to finish roughly unchanged or slightly lower, potentially marking the first annual decline since 2017.

Producers representing roughly two-thirds of global supply recorded a 3.5% decline during the first half and a 4.1% drop in the second quarter, according to Jefferies data cited by SP Angel. Chile, the world’s largest copper-producing country, suffered its weakest second quarter in nearly two decades and now expects annual output to fall 2.6%.

Related:

Copper has now advanced for 10 consecutive weeks on the London Metal Exchange.

To sum up, all of this only suggests a structurally bullish period for copper. Demand from electric vehicles, power-grid expansion and artificial-intelligence data centers is accelerating just as physical-market tightness constrains supply and pushes London prices higher.

Tyler Durden
Mon, 09/07/2026 – 11:35

via ZeroHedge News https://ift.tt/7q2YThg Tyler Durden

This Labor Day, A Look At Declining Role Of Unions In America

This Labor Day, A Look At Declining Role Of Unions In America

Authored by Jeremy Lott via The Epoch Times,

Labor Day, celebrated this year on Sept. 7, is a holiday in transition.
It was created by American labor unions in the 1880s. The federal government recognizing it as a national holiday under President Grover Cleveland helped unions to gain prominence.

Yet as unionization has declined, so too has the close association of the day with organized labor.

The Department of Labor’s website now calls it an “annual celebration of the social and economic achievements of American workers.”

Nelson Rivera of New York City is one such worker. He is an assistant supervisor in maintenance, a field he has toiled in for 23 years.

“Labor Day to me is just celebrating people that’ve been working all their lives, like 20 and 30 years,” he told The Epoch Times.

He said it was a day to “cook out with my family, have a good time with them, and relax.”

For many working families like Rivera’s, the Labor Day cookout is a regular event.

It’s also the occasion for many sales, the moment fashionistas have designated to mark the shift to fall colors, and the holiday after which many schools start.

Even that last part has faded, however, with the Pew Research Center finding in 2023 that more than 70 percent of students now start earlier.

America is less organized around Labor Day because American workers are less organized by unions than they used to be.

Only 10 percent of the total American workforce was unionized last year.

Among those, fewer than 6 percent of private-sector workers were unionized, according to government data from the Bureau of Labor Statistics.

The decades-long decline has been helped along recently by some Trump administration moves against public-sector unions.

On the state level, legislatures in red states are pushing against unions in several ways, while their counterparts in blue states are pushing back.

In percentage terms, it has been quite the fall. Unionization of the American economy stood at 20.1 percent in 1983. From the mid-1940s to the mid-1950s, the percentage of the U.S. workforce that was unionized was even higher than that, at more than 30 percent.

That means that the American economy has transformed over 70 years, from roughly one in three workers being unionized in 1955 to one in 10 in the most recent figures.

Last year’s unionization number was propped up by government workers, who the Bureau of Labor Statistics noted are organized at a rate “more than five times higher than the rate of private-sector workers,” or 32.9 percent.

Looking at the private sector alone, only slightly more than one in 20 workers were represented by a union.

Trump and Unions

President Donald Trump courted union voters during his three campaigns for the presidency, and the actions of his administration toward private-sector unions have been mixed.

At times, Trump has shored up the union position. He met with the International Longshoremen’s Association leadership as president-elect in 2024 and worked to avert a strike with an agreement to slow any job-replacing automation at East and Gulf Coast ports.

Other times, Trump has done things that unions generally opposed, such as firing the National Labor Relations Board’s Democrat-designated member Gwynne Wilcox in late January 2025.

The firing had to be litigated. That kept the regulatory body from having a necessary quorum for about a year. The lack of regulatory authority contributed to a growing backlog of thousands of cases, which made it very difficult for unions to press unfair labor practice claims.

Trump’s administration has been more oppositional to unions representing government workers.

With one executive order, for instance, the president sought to exclude the workers of 40 government agencies from collective bargaining. After much litigation, the administration has managed to cancel collective bargaining for the workers of several agencies.

In an April court filing, the National Treasury Employees Union said it expects to “lose tens of thousands of members” because of those actions.

The administration also took actions to make it easier to fire civil servants by reclassifying them, successfully urged somewhere in the neighborhood of 140,000 federal workers to take buyouts, and has floated a federal pay freeze for next year.

Unions representing government workers have shed many of their own workers. Collections fell off after the federal government stopped automatically deducting union dues from many workers’ paychecks and depositing them into union accounts.

States and Unions

Actions limiting government unions in ways great and small are also happening at the state level, particularly those controlled by Republicans.

For instance, this year the Idaho legislature passed a bill to prohibit school districts “from allowing taxpayer funds to promote teachers unions.”

The bill forecast that a few school districts “may experience a modest indeterminate increase in revenue,” seeing as how teachers’ unions are now “required to reimburse the school district for any time teachers spend on union-related activities during work hours.”

States with Democratic majorities are generally pushing the other way, as one act of the New Jersey legislature shows.

For the 2026-2027 school year, New Jersey schools are introducing mandated curriculum to turn social studies classes into primers on the past struggles of organized labor, including “notable strikes throughout history.”

Where Unions Have a Greater Impact

Yet the story for organized labor in America on this Labor Day is not only a story of decline. There are some successes as well that show how unions continue to exert influence.

Unions continue to push for and win some unionization elections.

And unions in a few sectors have found ways to buck the wider trend and have organized in numbers that are several times greater than in the economy as a whole.

The technical term for the percentage of the economy that is unionized is called union density.

Julia Cartwright is a senior research fellow in law and economics at the American Institute for Economic Research.

She told The Epoch Times that she expects that private-sector union density will either “stay flat or drift slightly lower over the next five years, from 5.9 percent in 2025 to somewhere in the 5.5-6 percent range by 2030.”

Currently, the transportation and infrastructure sectors “sit well above the private-sector average” of union density, Cartwright said, and supplied numbers from government data.

Workers at utilities, which manage significant infrastructure, are 17.8 percent unionized. Transportation and warehousing workers together are 13.6 percent unionized. Construction workers, who are responsible for servicing and building out a lot of infrastructure, are 11.1 percent unionized.

“These industries stay more heavily unionized because the usual union-avoidance playbook doesn’t work as well there,” she said, explaining that “the work can’t be relocated; you can’t offshore a port, a rail line, or a construction site.”

Cartwright said certain laws have also played a role in boosting unionization in these sectors.

Prevailing wage laws, mandated for federal contracting companies by the Davis-Bacon Act of 1931 and mimicked by several states, require “prevailing, often union-scale, pay on public projects, which erases nonunion contractors’ main bid advantage and keeps union contractors and their apprenticeship pipelines viable,” she said.

Parts of the transportation sector have a whole different set of laws regulating unionization, she noted.

The normal rules of the game under the National Labor Relations Act of 1935 treat single workplaces as bargaining units for the purposes of unionization elections.

Railroads and airlines are instead governed by the older Railway Labor Act with “bargaining units spanning an entire carrier’s system,” Cartwright said.

That makes it easier to unionize much larger percentages of those sectors. And more thorough unionization gives unions more leverage.

Rail and shipping are “chokepoint industries,” she said, “meaning industries positioned at narrow pass-through points in the economy where a stoppage cascades far beyond the firm itself.”

Cartwright used as an example a rail or port strike, which can “idle billions of dollars in capital and disrupt supply chains nationwide.”

The large sums of money at risk of disruption have “historically made accommodation cheaper for employers than confrontation.”

Construction, Transportation Trends

Peter Philips is an economist at the University of Utah who has also studied unionization in America. He foresees some strength ahead for unions in these sectors, but also some weakness.

“Union density in the construction sector benefits from construction booms,” he told The Epoch Times, and he thinks demand for data centers to power the growing AI sector fits that bill.

Philips predicted that far greater data center construction will redound “to the benefit of construction unions that will expand their membership to meet the demand.”

In contrast, he thinks the transportation sector is “more of a mixed bag.”

Philips said that economic booms benefit trucking, railroads and airline travel.

Yet trucking firms are finding themselves squeezed by higher diesel prices due to shipping problems through the Strait of Hormuz, and the AI boom could lead to the development of some driverless trucking down the road.

The expansion of driverless trucks, “if they are successfully introduced to the transportation sector,” is likely to “hurt long haul trucking employment, including possibly unionized truckers,” he said.

He thinks that Americans are bound to be skittish about at least some of this.

“It may be a while, if ever, that the public is going to be comfortable with and accept driverless 18-wheelers,” he said.

The contest he sees developing at trucking firms is between rising demand, the struggle to staff for that, and automation, which is one answer to the staffing problem.

Recent Union Gains

Drawing on the same government data as Cartwright and Philips, the AFL-CIO trumpeted the recent achievements of organized labor as a whole.

Union representation grew by 463,000 in 2025, bringing the total number of workers represented by union contracts to 16.5 million,” the union said in a news release earlier this year celebrating results that were the “highest in 16 years.”

The AFL-CIO noted “significant gains in health care, retail, education services and construction” and that unions have made headway in the South, which had been thought by many in organized labor to be hostile territory because of the states’ right-to-work laws.

However, even for all that effort, the percentage of America’s unionized workforce stayed essentially flat.

Cartwright cautioned that percentages of unionization can sometimes be misleading because the size of the American workforce changes over time.

“Unions have been adding members in absolute terms,” she told The Epoch Times, “but the nonunion workforce keeps growing faster, so union density stays roughly the same.”

Cartwright said this growing but still seemingly getting nowhere phenomenon was “starkest in 2022, when unions gained 273,000 members and density still fell because total employment grew by 5.3 million.”

That does not mean that unions are doomed to relative decline. What it does mean on this Labor Day is that unions and their supporters have their work cut out for them.

According to AFL-CIO President Liz Shuler, they are up to that challenge.

“In 2026, workers will continue to organize in every corner of the country and build power to fight for the lives they deserve,” she said.
Tyler Durden
Mon, 09/07/2026 – 11:15

via ZeroHedge News https://ift.tt/qn4TPzb Tyler Durden

Zelensky Expects War To Continue Through Winter, As Witkoff-Kushner Deliver ‘Upbeat Assessment’ From Putin Meeting

Zelensky Expects War To Continue Through Winter, As Witkoff-Kushner Deliver ‘Upbeat Assessment’ From Putin Meeting

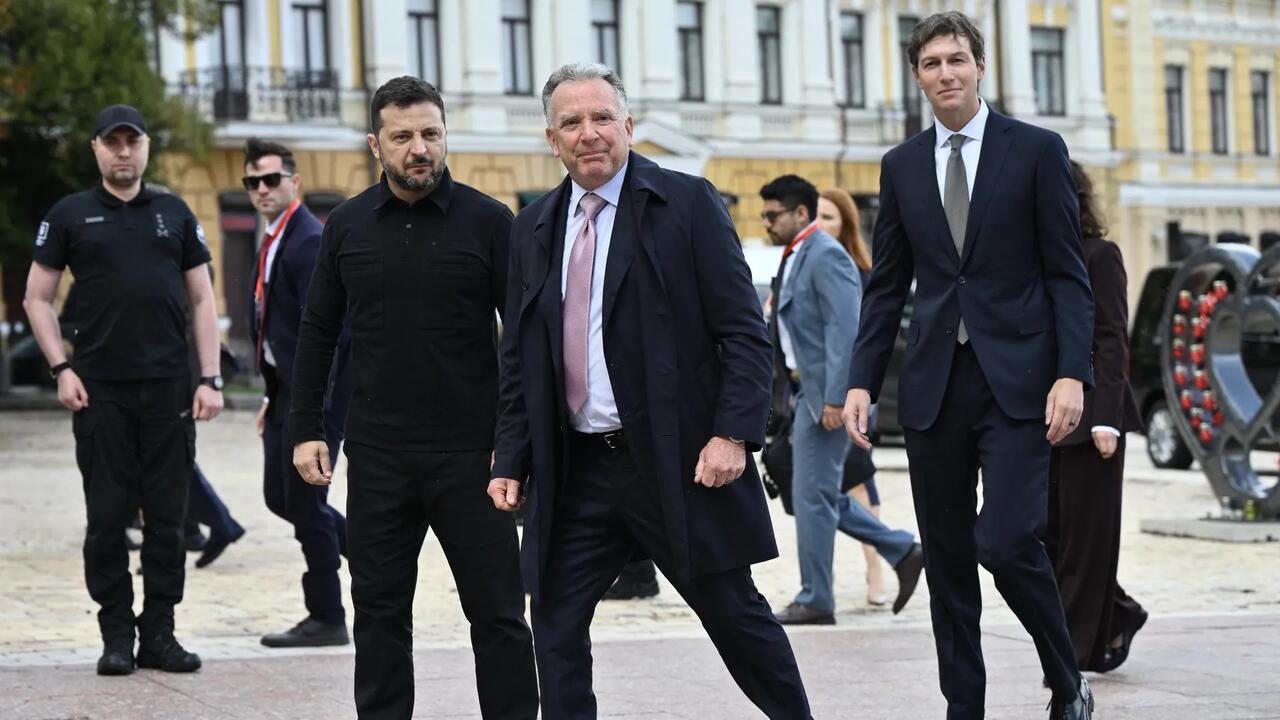
Despite Trump envoys Steve Witkoff and Jared Kushner having delivered ‘upbeat assessments’ (per AFP) to Kiev after meeting with President Putin in Moscow over the weekend, Ukrainian President Zelensky has told his citizenry to prepare for a brutal winter, as the war is set to continue through this period.

A senior Ukrainian presidential official said Sunday that the US team brought new, “more effective” proposals for ending the war. “It’s not the same as it was before. This one now is more effective. They’re still talking. This is actually the most important part,” the official said to AFP.

AFP via Getty Images

This marked Witkoff-Kushner’s first trip to Kiev – as they’ve been playing point for Trump efforts at negotiating the end to conflicts from the Middle East to Gaza to Eastern Europe. However, many have pointed out they are un-elected, not formally appointed, and hold no official government offices – and do not have prior track records as high level diplomats. 

Zelensky after being briefed on US talks with Putin remarked: “We very much hope that we will be able to reach agreements with our American partners, and we are counting on the support of our European partners if the war continues in winter — and this is how it appears at the moment.”

This comes after the Kremlin reportedly told Americans Saturday it was feeling “confident” its forces would advance more, deeper into Ukraine from eastern territories that Russia already holds.

Kushner said: “Hopefully this trip has come out with some new ways to advance forward. I think we’ve learned a lot from the trip.”

It’s unlikely that President Putin takes these two men very seriously, especially Trump’s son-in-law, who seems to hold this top envoy position for no other reason than being family. And of course Witkoff is a real estate mogul. Both Kushner and Witkoff are Jewish – which has some bearing on failed Iran negotiations, as well as prior Gaza peace efforts – given Tehran doesn’t trust them, but sees them as having divided loyalties. The Kushner family has for decades been close personal friends of Netanyahu, with the Israeli leader having on occasions stayed at their private residence.

Hundreds of thousands dead in the Ukraine proxy war, which holds the potential to escalate into nuclear confrontation with NATO… and the guys that Trump sends sit and ruminate about the “incredible stories and memories” they will share in retirement:

Trump had promised to end the Ukraine war from his very opening days in office, which of course proved absurdly unrealistic. But he did energize the MAGA base by placing this as a top priority.

However, the reality remains: the US has continued providing deep intelligence assistance to Ukraine, it has continued to approve missile and other weapons transfers to Kiev, and has given a greenlight for Ukraine to send long-range drones against sensitive assets on Russian soil. Halting these things could be an actual catalyst toward peace settlement, but so far by all appearances these US support programs are going strong.

T-shirts…

Tyler Durden
Mon, 09/07/2026 – 10:50

via ZeroHedge News https://ift.tt/XEQi0Lj Tyler Durden

Help Workers by Breaking Down Barriers to Labor Mobility

NA

Each Labor Day since  2021, I have written posts explaining how breaking down barriers to labor mobility can help many millions of workers around the world. The main points everything  last year’s post are just as relevant today. So I am reprinting it with some updates and modifications, many of them related to the awful deterioration in immigration policy over the last year:

Today is Labor Day. As usual, there is much discussion of what can be done to help workers. But few focus on the one type of reform that is likely to help more poor and disadvantaged workers than virtually anything else: increasing labor mobility. In the United States and around the world, far too many workers are trapped in places where it is difficult or impossible for them to ever escape poverty. They could vastly improve their lot if allowed to “vote with their feet” by moving to locations where there are better job opportunities. That would also be an enormous boon to the rest of society.

Internationally, the biggest barriers condemning millions to lives of poverty and oppression are immigration restrictions. Economists estimate that eliminating legal barriers to migration throughout the world would roughly double world GDP – in other words, making the world twice as productive as it is now. A person who has the misfortune of being born in Cuba or Venezuela, Zimbabwe or Afghanistan, is likely condemned to lifelong poverty, no matter how talented or hardworking he or she may be. If they are allowed to move to a freer society with better economic institutions, they can almost immediately double or triple their income and productivity. And that doesn’t consider the possibility of improving job skills, which is also likely to be more feasible in their new home than in their country of origin.

The vast new wealth created by breaking down migration barriers would obviously benefit migrants themselves. But it also creates enormous advantages for receiving-country natives, as well. They benefit from cheaper and better products, increased innovation, and the establishment of new businesses (which immigrants create at higher rates than natives). Immigrants also contribute disproportionately to scientific and medical innovation, including vaccines and other medical treatments that have already saved millions of lives around the world.

The Trump Administration’s massive assault on immigration of virtually every kind is predictably harming both migrants and native-born Americans, condemning hundreds of thousands of the former to a lifetime of poverty and oppression, and denying the latter the growth and innovation immigration facilitates. Most recently, thanks in part to a badly flawed Supreme Court decision, it has depriving hundreds of thousands of Haitians and others of legal status, thereby gravely harming both these migrants and the many US industries that depend on them.

Similar, though somewhat less extreme, barriers to labor mobility also harm workers within the United States. Exclusionary zoning prevents many millions of Americans – particularly the poor and working class – from moving to areas where they could find better job opportunities and thereby increase their wages and standard of living. Occupational licensing further exacerbates the problem, by making it difficult for workers in many industries to move from one state to another.

Breaking down barriers to labor mobility is an oft-ignored common interest of poor minorities (most of whom are Democrats), and the increasingly Republican white working class. Both groups could benefit from increased opportunity to move to places where there are more and better jobs and educational opportunities available. Much can be done to curb these problems through a combination of political action, and litigation under both  federal and state constitutional law.

As with lowering immigration restrictions, breaking down domestic barriers to labor mobility would create enormous benefits for society as a whole, as well as the migrants themselves. Economists estimate that cutting back on exclusionary zoning would greatly increase economic growth. Like international migrants, domestic ones can be more productive and innovative if given the opportunity to move to places where they can make better use of their talents.

Many proposals to help workers have a zero-sum quality. They involve attempts to forcibly redistribute wealth from employers, investors, consumers, or some combination of all three. Given that virtually all workers are also consumers, and many also have investments (e.g. – through their retirement accounts), zero-sum policies that help them in one capacity often harm them in another. Breaking down barriers to labor mobility, by contrast, is a positive-sum game that creates massive benefits for both workers and society as a whole; it similarly benefits both migrants and natives.

The same is true of breaking down barriers to the mobility of goods. Tariffs and other trade restrictions harm many more workers than they benefit, by increasing prices (which disproportionately hurt lower-income workers), and increasing the cost of inputs used by domestic industries (leading to lower employment levels and wages). In February, the Supreme Court struck down Trump’s massive and unconstitutional IEEPA tariffs in a case I helped litigate. But the administration has sought to replace them with equally illegal and harmful tariffs enacted under various pretext, such as combating “forced labor” or addressing “balance of payment deficits.” Litigation on these policies is ongoing.

Some on the left point out that, if investors are allowed to move capital freely, workers should be equally free to move, as well. It is indeed true that, thanks to government policies restricting labor mobility,  investment capital is generally more mobile than labor. It is also true that the restrictions on labor mobility are deeply unjust. In many cases, they trap people in poverty simply because of arbitrary circumstances of birth, much as racial segregation and feudalism once did. The inequality between labor and capital, and the parallels with segregation and feudalism should lead progressives to put a higher priority on increasing labor mobility.

At the same time, it is worth recognizing that investors and employers, as a class, are likely to benefit from increased labor mobility, too. Increased productivity and innovation create new investment opportunities. The biggest enemies of both workers and capitalists are not each other, but the combination of nativists and NIMBYs who erect barriers to freedom of movement, thereby needlessly impoverishing labor and capital alike. Despite conventional wisdom to the contrary, even current homeowners often have much to gain from curbing exclusionary zoning policies that block the construction of housing needed by workers seeking to move to the region.

On the right, conservatives who value meritocracy and reject racial and ethnic preferences, would do well to recognize that few policies are so anti-meritocratic as barriers to mobility. The case for ending them also has much in common with the case for color-blind government policies, more generally. A number of other conservative values also reinforce the case for curbing both domestic NIMBYism and immigration restrictions. Right-wingers would also do well to recognize that most workers benefit from free trade, and are harmed by protectionism.

There are those who argue against increasing labor mobility, either on the grounds that existing communities have an inherent right to exclude newcomers, or because allowing them to come would have various negative side-effects. I address these types of arguments here, and in much greater detail in Chapters 5 and 6 of my book Free to Move: Foot Voting, Migration, and Political Freedom. As I explain in those earlier publications, nearly all such objections are wrong, overblown, or can be ameliorated by “keyhole solutions” that are less draconian than exclusion. In addition, the vast new wealth created by breaking down barriers to mobility can itself be used to help address any potential negative effects. In the book, I also push back against claims that mobility should be restricted for the benefit of those “left behind” in migrants’ communities of origin.

In recent years, there has been important progress on reducing exclusionary zoning. Several states have also enacted occupational licensing reform, which facilitates freedom of movement between states. But there is much room for further improvement on these fronts. And when it comes to international migration, we are in a period of horrific regression.

Workers of the world, unite to demand more freedom of movement!

The post Help Workers by Breaking Down Barriers to Labor Mobility appeared first on Reason Magazine.

from Latest – Reason Magazine https://ift.tt/GdinHVl
via IFTTT

GOP Bets On Trumpapalooza To Defy Midterm History

GOP Bets On Trumpapalooza To Defy Midterm History

Authored by Carolina Lumetta via RealClearPolitics,

Texas-based Republican strategist Rebecca Trahan is excited to see the first-ever GOP midterm convention come to Dallas next week. More specifically, she hopes it will bring yet more national attention and dollars to the Senate campaign for state Attorney General Ken Paxton.

“I think [the convention] can be very motivating. I hope that the event does encourage and get people to get out and vote,” Trahan told RealClearPolitics. “I hope that it drives a lot of money to the Paxton campaign because they really need it, and I know that Texas really needs Ken Paxton as the next senator considering our options.”

Trahan says Paxton’s Democratic opponent James Talarico is a more formidable challenger than many Republicans realize. She said the convention is a welcome burst of energy onto the scene but would be better if it were more accessible. The two-day event will not be aired in full on national television networks, and it competes with the beginning of the school year and the start of football season on the two nights of speeches.

“I really applaud the RNC for doing everything that they can to help Texas candidates, and especially to help Ken Paxton, because we need it,” Trahan said.

But she’s not attending the convention either.

“For me, if I’m going to a fundraiser, I prefer that it be a little bit more private,” Trahan said. “I love conventions, but there is so much work to be done just this weekend alone, and block walking and phone banking. So I chose to stay back and do that.”

The Republican National Committee promised a “Trumpapalooza” as the president takes the stage on both convention nights. Several Republican candidates have hemmed and hawed on whether they’ll attend the rally-like event, and the RNC has opened attendance to the public, hoping to gin up both base and prospective voter support.

“We are trying to reach those low- and mid-propensity voters that came out for President Trump in 2024, and we’re trying to communicate to the American people the contrast that they have on the ballot this cycle,” RNC spokeswoman Natalie Baldassarre told RCP.

Vice President JD Vance previewed the party’s message during a White House press briefing Thursday. For the past year, the Trump administration has highlighted the One Big Beautiful Bill, rebranded as the Working Families Tax Cuts. In recent weeks, they’ve argued that Democrats who opposed the legislation would essentially be raising taxes if they win and would try to reverse Trump’s actions over the past two years.

“My elevator pitch is actually very simple,” Vance told reporters. “Do you want to live in a country that has safety and security and prosperity? If the answer is yes, and I think most Americans do, then vote for congressional Republicans over congressional Democrats on every single issue. The Democrats have taken the side of fraudsters, of criminals, and of far-left interest groups over the side of the American people.”

But the strategy of hosting a midterm convention in Texas in September could be a double-edged sword.

“I don’t know how much I want to be part of this,” one Republican House member told RCP. “It’s just going to be a highly orchestrated Trump thing where they’ll trot out some members.”

Many Republican candidates, particularly those in tight races, have either declined to attend the convention due to scheduling issues or have not revealed their plans, according to reporting from Politico and CNN. During a midterm year, even one or two days spent away from the campaign trail is considered wasted time. To that effect, House Speaker Mike Johnson already canceled the final weeks of the House session this month so that members may remain in their districts.

The low level of enthusiasm does not appear to be worrying the White House. Vance said the point of the convention is to bring the full force of the Trump administration to help the GOP, which does not necessarily require candidates to be on the stage.

“That doesn’t concern me,” Vance said during the briefing. “We can make the argument as much as possible that if you elect congressional Democrats, you’re going to see higher prices, worse energy, higher taxes, and more fraud. The president and I can go and make that argument on national TV. We don’t need a congressman in a tight race to be there in all cases.”

Conventions in midterm years are often glorified revelries with little concrete purpose, especially when the identity of the party’s eventual presidential nominee is unknown. Trump first publicly floated the idea of a midterm convention last year. Then, the RNC voted during its January annual meeting to change the charter rules to allow for such an event. Trump confirmed the date and location in another Truth Social post in June.

While the GOP has never done something like this before, Democrats were once quite practiced at it. The party would often host a mid-cycle convention until the mid-1980s, when then-Democratic National Committee chairman Paul Kirk shuttered the tradition. He complained that would-be presidential candidates used the stage to attract attention for themselves rather than all the races down-ballot that needed support. The entire event he summed up as “places for mischief.”

This year, the DNC again teased that it might return the practice, but in its own annual meeting, members shot down the idea. DNC Executive Director Roger Lau said in a statement that the party had “baited” the GOP into throwing money down the drain for a midterm convention, giving the DNC an advantage in spending. But that strategy might not have panned out. The RNC reported a record $130.3 million in cash on hand by the end of July. The DNC reported roughly $16 million at the same time, along with nearly $18 million in debt.

Most congressional Republicans are paying roughly $25,000 each to attend the convention, though each state party manages its own ticket packages. Other affiliated organizations, such as the National Republican Congressional Committee, are offering additional perks like breakfast with House leadership and special access for up to $100,000, according to an NRCC flyer first reported by Politico. The RNC also designated tickets for state parties, which then determined how to distribute them. Instead of delegates, the seats will be filled with members of the public, according to the RNC.

RNC Chair Joe Gruters told Newsmax this week that the convention will be a landing place for the party’s messaging. He appeared optimistic that of the 35 competitive House races this cycle, Republicans can defy conventional wisdom and defend the congressional majority.

“We think we can defy history and we have the right candidates,” Gruters said. “We have the messaging, we have the resources to put behind that messaging, and so, we’re well on our way.”

The messaging will focus on key portions of the president’s agenda, including last year’s tax cuts, border enforcement, energy policy, trade, and more. But it will have to dodge some pitfalls, such as the ongoing war with Iran, high inflation and gas prices, a controversial deal to subsidize Venezuelan beef, concerns about data centers, and the president’s sinking approval ratings. Vice President JD Vance will keynote the first night, and the president will close out Thursday night with his own address.

Tyler Durden
Mon, 09/07/2026 – 10:25

via ZeroHedge News https://ift.tt/WOTq68M Tyler Durden

Huawei Crashes Apple’s Big Launch Week With $3,000 Trifold Smartphone

Huawei Crashes Apple’s Big Launch Week With $3,000 Trifold Smartphone

Two days before Apple’s big launch event on Wednesday, when the company is expected to debut its long-awaited foldable iPhone, Huawei Technologies and Xiaomi are unveiling their premium foldable smartphones.

Huawei on Monday unveiled its Mate XT 2, a trifold smartphone that unfolds into a 10.2-inch tablet. The starting price is $2,980, representing a 10% increase over its predecessor.

Huawei Executive Director Richard Yu attributed part of that increase to the big memory squeeze that has sent prices skyrocketing. Despite its premium price, the entry-level device comes with 16GB of memory and 256GB of storage. 

Xiaomi is set to launch a rival foldable phone later today, while Apple’s foldable iPhone, expected to debut on Wednesday, could be called the iPhone Ultra and cost upwards of $2,500.

Yu told reporters earlier that the “real challenge right now is pricing, because memory costs have risen sharply. We adopted a lot of new technology, and the cost pressure has been enormous.”

The launches of premium foldable phones from the three major brands this week come amid mounting headwinds across the global handset market. Counterpoint forecasts a 14% drop in global smartphone shipments this year. Chinese manufacturers are particularly exposed because of their reliance on budget handsets.

Counterpoint analyst Ivan Lam said Apple has the “world’s biggest premium device installed base,” adding, “Its foldable will sell well and rapidly grab market share.” He also noted that the new handset could spur broader consumer demand, giving rivals a lift.

Smart Analytics Global forecasts that Apple could capture 41% of worldwide foldable sales next year. Its entry will undoubtedly intensify competition across the foldable space.

However, Nikkei Asia reported last week that production of foldable iPhones remains limited ahead of this week’s launch.

“Apple has very high quality requirements and added an extra trial run in August ahead of actual production. However, production is ramping up slowly, with output currently at only a few hundred units a day in late August. That initial volume could be challenging to meet market demand,” one supply chain manager told the Japanese news outlet.

With U.S. gasoline prices averaging above $4 a gallon nationally and squeezing household budgets, the iPhone Ultra’s high price tag could pose a major test of consumers’ willingness to spend on premium upgrades. For Apple, under new leadership with John Ternus at the helm, the key question is whether the foldable design offers enough value to persuade consumers to upgrade. Then again, there are always buy-now, pay-later options.

Tyler Durden
Mon, 09/07/2026 – 10:00

via ZeroHedge News https://ift.tt/KM0I3ea Tyler Durden

Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

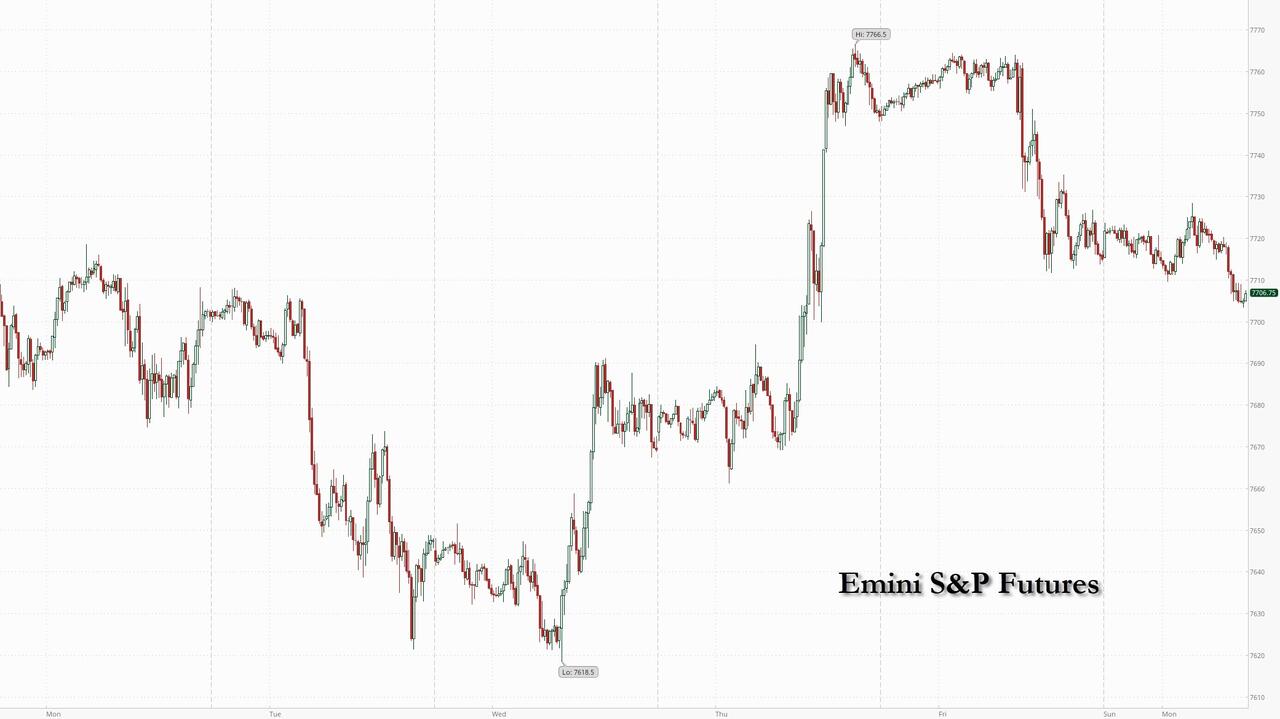
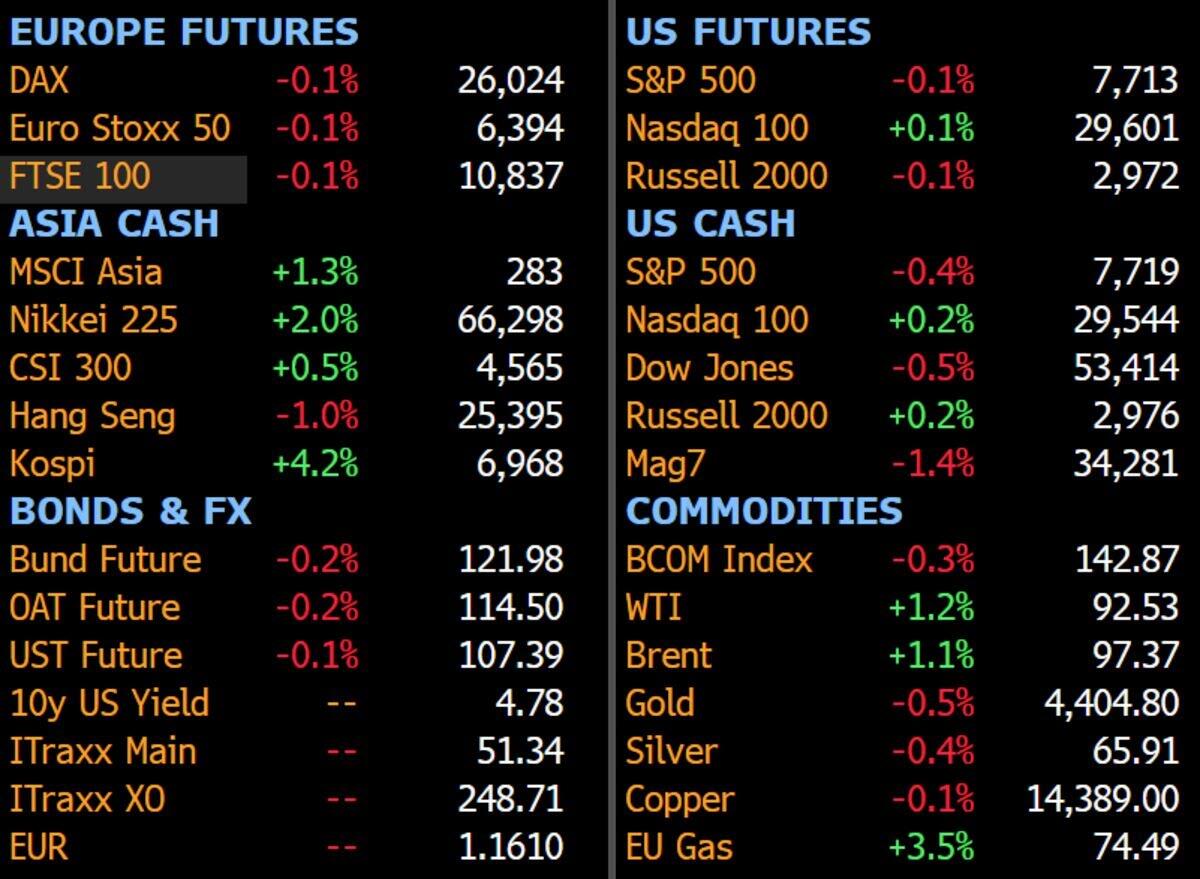
US stock futures slipped in cautious, low volume trading as the latest Middle East escalation pushed oil prices higher, lifting bond yields in Europe and Asia. As of 9:00am ET, S&P futures were down 0.2% with Nasdaq futures modestly in the red despite solid performance for tech stocks earlier in the session, which helped the Kospi surge more than 4.6% – its second biggest jump since the Situational Awareness takeover by Citadel – and Nikkei jumped almost 2% as OpenAI’s GPT-6 Astra debut reinvigorates the Asian semiconductor rally. Taiex climbs about 1.5% and ChiNext soars 2.6% (as discussed overnight, China may be the next Gamma Squeeze target). Hang Seng underperformed peers with a 1% loss as Chinese tech stocks retreat in Hong Kong. Brent crude rose above $97 a barrel following the largest exchange of tanker attacks yet between Iran and the US. Traders also assessed reports of hits on Saudi Arabian oil infrastructure and a potential accord between Iran and Oman to manage shipping through the Strait of Hormuz. In FX, the yen strengthened to its highest level since February, surpassing the peak reached after July’s intervention. The dollar fell 0.2%. Cash trading in Treasuries and US equities was closed for Labor Day. US markets are closed for Labor Day. 

In corporate news, an Amazon.com Inc. cargo plane overran a runway at Miami International Airport and burst into flames on Sunday, killing at least five people and temporarily shutting down the airport’s runways.

  • Jaguar Land Rover Automotive Plc will slash some 4,000 jobs as Britain’s largest carmaker grapples with US tariffs, the fallout of a crippling cyberattack and intense competition.
  • Novo Nordisk A/S stopped two more trials for its experimental heart disease medicine, in a further blow to the drug’s prospects.
  • Abu Dhabi National Oil Co. is in talks with the biggest refining companies in Thailand and Africa to invest in their businesses.
  • Uber Technologies Inc. has hired banks to hold calls with investors this week for a debut euro bond sale.
  • Novartis AG suffered a second trial disappointment within a week after the Swiss pharma group’s potential blockbuster heart drug failed in a final-stage study.

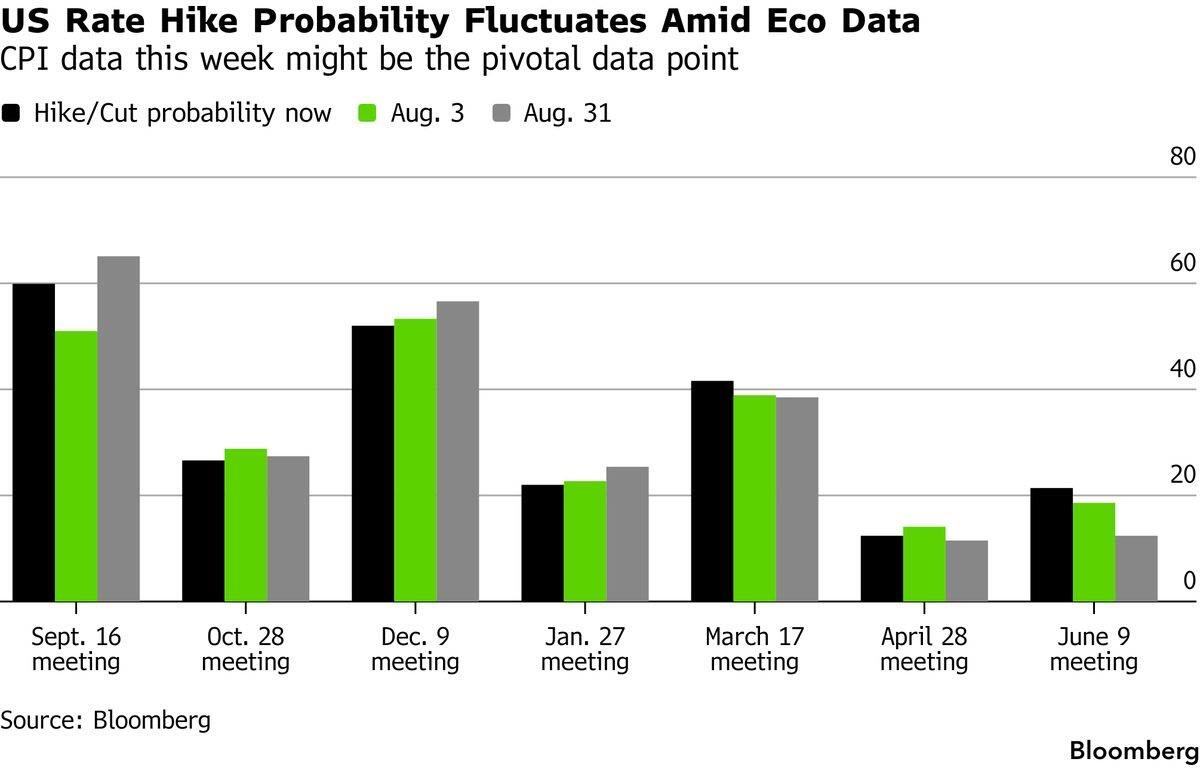
US cash trading and individual stock futures are shut today for the Labor day weekend. For anyone catching up after a break, Friday’s US jobs report did the early work on this week’s story. Payrolls rose 162,000, blowing past estimates, and pushed the market-implied odds of a Federal Reserve rate hike on Sept. 16 to a little above 60% from around 50% before the print.

That leaves Friday’s CPI (and to an extent Thursday’s PPI) as the real swing factor for a Fed that’s held steady for five straight meetings. The European Central Bank adds its own test Thursday, with markets pricing a near-certain quarter-point hike to a 2.50% deposit rate. Between the two central banks and Friday’s CPI, this is the week Europe has to trade around.

“Markets will be adjusting their positioning heading into the Fed’s blackout period. The risk is the Fed turning hawkish and that will be reflected in equities,” said Geoff Yu, a senior macro strategist at BNY. “Bond markets will remain nervy and we remain focused on fixed-income volatility.”

While economic data will likely be the biggest catalyst for markets this week, earnings will also help shape the outlook for key equity sectors. Results from Oracle Corp. and Adobe Inc. on Thursday will give investors a fresh read on AI infrastructure demand and the threat the technology poses to software makers. For now, the earnings backdrop remains supportive. Investors should buy any dips in equities given a robust earnings outlook, said JPM strategists. Even moderate central bank tightening would be unlikely to derail the positive backdrop for stocks unless inflation expectations change materially, said the team led by Mislav Matejka. “As corporate profits remain on an uptrend, any bout of weakness in equity prices would leave them cheaper,” the strategists wrote. “We believe one should continue using the dips to add.”

The Stoxx 600 struggled for direction, with economically sensitive sectors among the biggest decliners as inflation concerns drove bond yields higher. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. Here are the biggest movers Monday:

  • Nordex shares rose as much as 12%, the most in over four months, after being upgraded to buy at BofA Global Research
  • SigmaRoc rose as much as 13%, the most since March 2021, after the lime and minerals group released its interim results and announced the acquisition of Lithuanian dolomite business AB Dolomitas
  • Lottomatica shares gained as much as 8.2%, hitting the highest since June, after the Italian gaming company quantified the boost to online earnings it expects from the proposed acquisition of Spanish rival Cirsa Enterprises
  • Infineon shares rose as much as 3.9% as MP Capital Markets upgraded the stock to buy from hold
  • Burkhalter shares rose as much as 6.7%, the most since March 2022, after the Swiss building technology services company reported results
  • Novartis shares fell as much as 3.9% after the Swiss pharma group’s potential blockbuster heart drug, pelacarsen, failed in a final-stage study
  • Schindler dropped as much as 3.6% after Goldman Sachs gave the elevator and escalator specialist its only sell rating, downgrading from neutral, citing lower growth and earnings progression compared to the wider sector
  • Tomra shares fell as much as 10%, while Norwegian-listed peer Envipco also slumps, after France abandoned plans to impose a mandatory deposit return system for plastic bottles, introducing doubts over a potential growth catalyst for the stocks
  • Hollywood Bowl shares dropped as much as 6%, the most since May 2025, after analysts at Deutsche Bank cut their price target and warned the summer drought created “less-than-ideal conditions” for the provider of indoor family entertainment

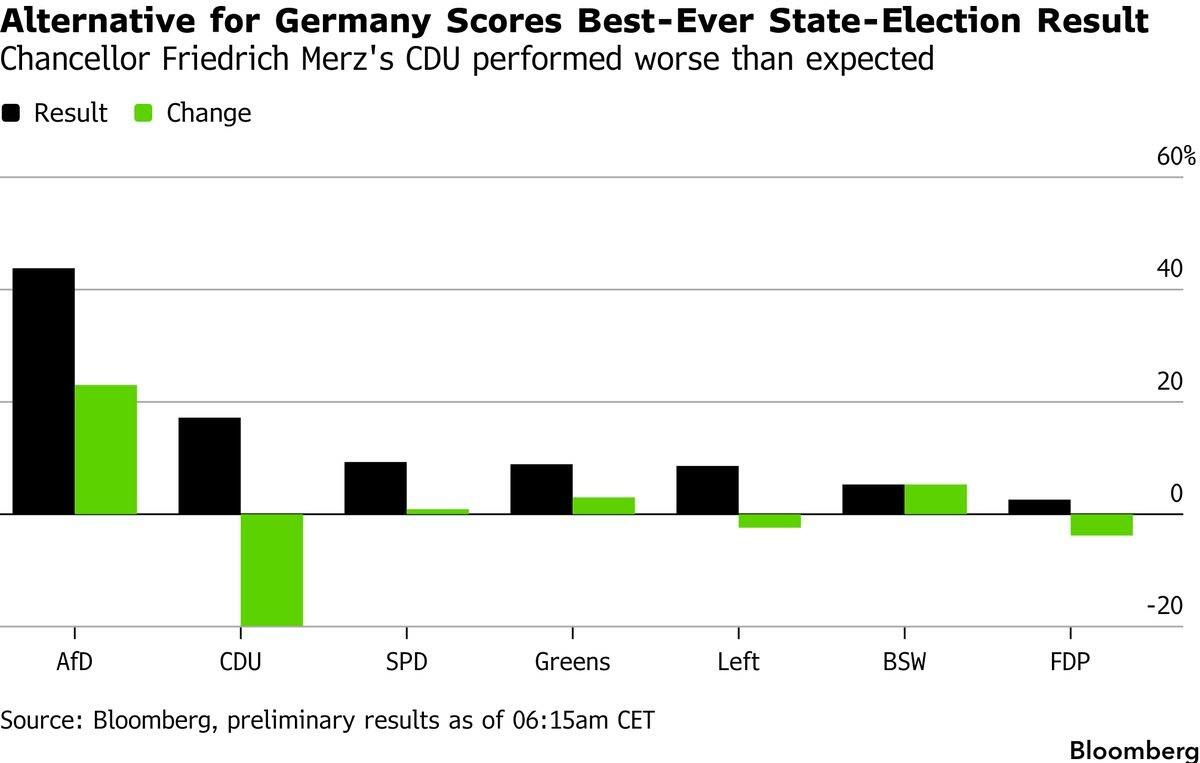
German establishment politics, and specifically Merkel’s pro-immigration legacy, suffered a crushing blow over the weekend, after the conservative Alternative for Germany scored its best-ever result in a state election on Sunday, delivering a powerful blow to liberal Chancellor Friedrich Merz. The AfD secured 44% of the vote in Saxony-Anhalt. In the UK, the government signaled it won’t provide financial support to limit job losses expected to be announced at Jaguar Land Rover this week.

South Korea’s memory heavyweights were standouts in Asia as the release of OpenAI’s GPT-6 model continued to fuel renewed enthusiasm for AI. Driving the tech rally is OpenAI’s plan to release a new model, GPT-6, pitched as a milestone toward artificial general intelligence. That pushed the Philadelphia Semiconductor Index up 3.4% on Wall Street Friday and has SK Hynix and Samsung leading the advance in Asia Monday. The enthusiasm isn’t universal though. Hong Kong’s Hang Seng and its tech gauge both slipped into the red despite the Nikkei and Kospi seeing solid gains.

The dollar initially ticked higher, but then retreated following another surge in the yen which pushed the USDJPY as low as 154, down almost 200 pips overnight. The Korean won extended winning streak to around two-year high. T-note futures are about 1/32 softer near 107-14 with cash Treasuries closed for Labor Day. Bund futures are ~15 ticks lower after German far-right party AfD wins state election. Aussie curve bear flattens with 3-year yield ~3 bps higher. WTI crude futures climb 1% to near $92.40; gold sheds almost $30 to below $4,400-handle.

The notable overnight mover was again the yen, which strengthened to its highest level since February, surpassing the peak reached after coordinated intervention by Japan and the US. The Japanese currency suddenly extended gains, up as much as 1.4% to 154.06 against the dollar in London trading. There was no clear driver for the move, with some traders pointing to the US holiday helping to exaggerate the moves while others mentioned the break of the key 155 per dollar level as a reason.  The yen’s break below 155 is significant given the level previously acted as a floor following past intervention episodes,” said Masahiko Loo, senior fixed income strategist at State Street Investment Management.

Large stop-loss orders below the 155-per-dollar level were triggered and options dealers were forced to sell dollars, adding to the yen’s gains, according to a trader familiar with the transactions who asked not to be identified because they aren’t authorized to speak publicly.

China, separately, said it’s injecting 300 billion yuan ($45 billion) into its largest banks and insurers, its biggest recapitalization in almost two decades, with only a modest share reaction so far. 

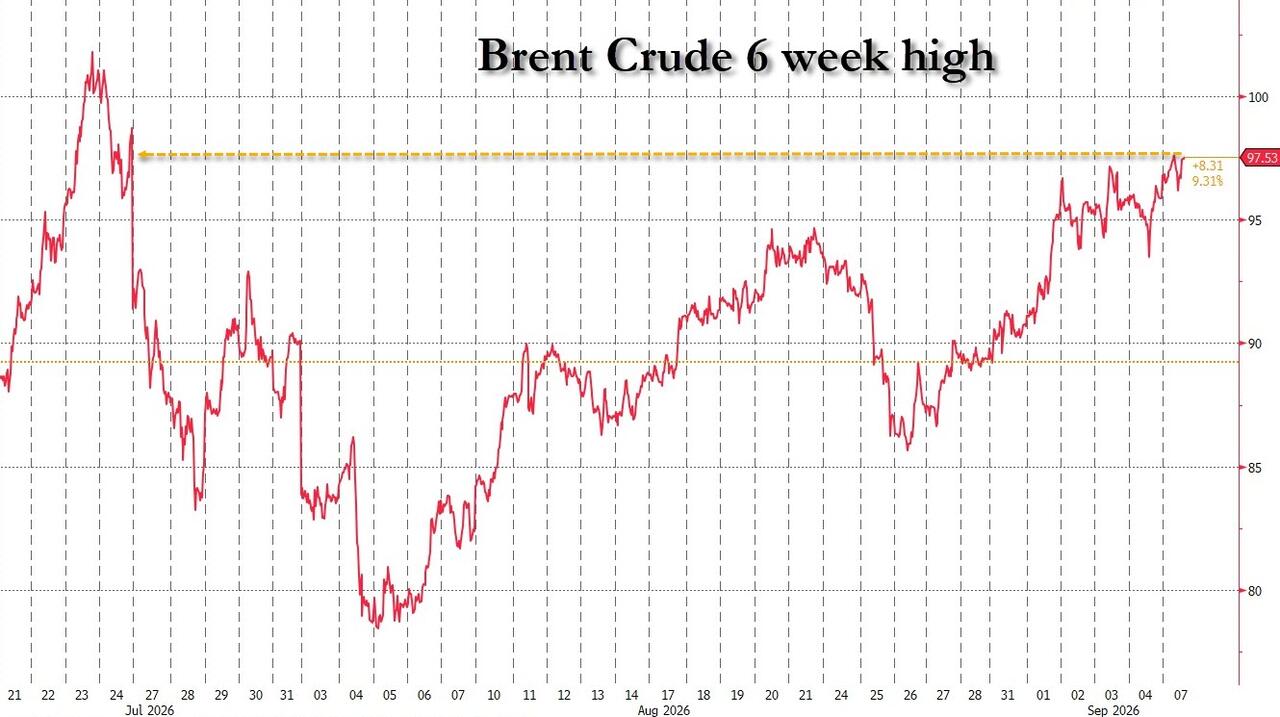
In commodities, oil advances, with Brent futures are trading at a 6 week high, above $97 a barrel, after US attacks on Iranian tankers and Tehran’s threat of a new restricted zone outside the Strait of Hormuz. Over the weekend, Iran said it hit three US-linked ships in retaliation for American attacks on Iranian tankers. The US military earlier said it struck three Iranian crude tankers, in response to the IRGC targeting two US Navy warships with ballistic missiles. European natural gas prices surge. Meanwhile, Ukraine is resigned to Russia’s war dragging on through another tough winter.

In rates, japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month. Treasury futures edge down. There’s no trading of cash Treasuries worldwide on Monday because of a US public holiday.

Market Snapshot

Top Overnight News

  • Saudi Aramco’s oil facilities in the Saudi Arabian city of Jizan have been attacked only a month after a separate strike temporarily knocked out some production at its refinery.: FT
  • Iran says US energy companies’ facilities are ‘exposed’: RTRS
  • UAE says its energy exports will not be ‘held hostage’ by Iran war: RTRS
  • Several Qatari liquefied natural gas tankers are heading back toward the Persian Gulf, a sign the supplier may be positioning vessels for a resumption of exports through the Strait of Hormuz: BBG
  • The Alternative for Germany scored its best-ever result in a state election on Sunday amid growing public discontent with the political establishment, delivering a powerful blow to Chancellor Friedrich Merz: BBG
  • AI could pose ‘existential’ risk to humanity, UN rights chief warns: RTRS
  • From dance floor to war: China readies humanoid robots for combat: RTRS
  • Japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month, despite concern in Washington over the impact of Treasury sales on long-term yields: BBG
  • The South Korean won advanced to its strongest level in nearly two years Monday, helped by a rally in semiconductor stocks and continued foreign inflows into the country’s benchmark equity index: BBG
  • Nepal rescuers focus on 900 hydropower workers, 121 could be trapped in tunnels, officials say: RTRS
  • German industrial production declined the most in almost a year, marking an unexpected setback to the recovery of Europe’s biggest economy: RTRS
  • Fed’s Hammack (2026 voter) said on Friday that Fed policy is not restrictive and inflation is too high, while she stated local contact views indicate now is the time for a Fed hike to control inflation.
  • Huawei launches new foldable smartphone; Xiaomi and Apple set to follow: RTRS
  • Warning signs abound for Republicans as midterm campaign begins final sprint: RTRS
  • President Trump said on Friday that they are taking action to help cattle ranchers and signed an order that allows ranchers to process their own beef, while small, medium, and large ranchers can sell to consumers, and he also stated that meatpackers have been charging unsustainable prices.
  • There were multiple casualties after an Amazon (AMZN) cargo plane overran the runway and struck vehicles whilst landing at Miami International Airport, while the Miami-Dade County Sheriff announced that at least five people have been confirmed dead.

Iran Headlines

  • US launched strikes against three Iranian crude oil tankers on Saturday, which destroyed one, in retaliation for the IRGC targeting US Navy warships with ballistic missiles.
  • Iran’s navy said it targeted three oil tankers that were travelling through unauthorised routes in the Strait of Hormuz and three additional US vessels in other areas.
  • US President Trump said on Friday that they do intermittent strikes in Iran and that the Iran issue is a military conflict, while he added that they may hit Pickaxe Mountain very soon. Trump warned that if anything goes badly with Iran, they may hit them hard and have essentially taken over Iran. He also claimed there have been no shootings for days and there are no mines in the Strait.
  • US Energy Secretary Wright said a nuclear deal with Iran may not be achievable in the near term and military action may be needed to address threats from Iran, according to ABC News.
  • Iran’s top security official Rezaei said Iran and Oman will sign agreed Strait of Hormuz passage maps in the coming days and that Iran will commit to keeping the Strait of Hormuz open when the US neither threatens Iran nor attacks it. Rezaei also stated that they will announce in the coming days and weeks a restricted zone outside the Strait of Hormuz that starts from the US Navy’s blockade line and extends through the strait into the Persian Gulf, and any ship identified entering this zone with the intention of passing through the strait will be added to the sanctions list. Furthermore, he said that Iran tested an Iranian anti-ship missile above a US warship for the first time and claimed the missile created ‘hell’ for the Americans ‘and they fled’.
  • Iranian Parliamentary Speaker Ghalibaf warned that Iran’s response to any attack against its interests and security would be faster, heavier and more painful.
  • Iran’s Foreign Ministry said the US-led war is disrupting global oil trade and costs, while it added that US aggression is causing instability in the Strait of Hormuz.
  • Israeli military announced that it struck southern Lebanon after Hezbollah launched drones towards Israeli soldiers in the security zone. Israel’s army also issued an evacuation warning to residents of a building in Deir Zahrani, southern Lebanon.
  • Israeli Finance Minister Smotrich said PM Netanyahu ordered the evacuation of certain settlement outposts in the West Bank. It was separately reported that Israel conducted an airstrike on eastern Gaza City with four missiles.
  • Joint statement by UAE, Saudi Arabia, Qatar, Jordan, Indonesia, Pakistan, Turkey and Egypt Foreign Ministers strongly condemned statements made by Israel’s National Security Minister Ben-Gvir and Defence Minister Katz regarding the displacement of Palestinians.
  • Yemeni armed forces said they thwarted an attempt by Houthis to infiltrate the Dabab front, while they announced that warplanes struck Houthi positions in Balhaf and south of Hodeidah.

A more detailed look at global markets courtesy of newsquawk

APAC stocks traded mixed as the region reflected on the recent strong US jobs data and subsequent Fed rate hike bets, as well as the US and Iran tit-for-tat attacks on vessels in the Strait of Hormuz. ASX 200 was little changed as resilience in the energy, resources, materials and mining sectors is offset by underperformance in tech, utilities and telecoms, but with downside in the index cushioned by support at around the 9,000 level. Nikkei 225 gapped above the 66,000 level with tech-related stocks heavily represented in the list of biggest gainers in the index. KOSPI outperformed amid firm gains in the semiconductor giants, including SK Hynix, which is said to be sharply increasing the production share of its sixth-generation 10nm-class 1c DRAM. Hang Seng and Shanghai Comp lagged with the Hong Kong benchmark pressured amid underperformance in the likes of Baidu and Xiaomi, while the big banks also declined after reports that ICBC and AgBank plan large A-share placements to raise CNY 100bln and CNY 160bln, respectively, as part of a Beijing-led CNY 360bln capital injection in financials.

Top Asian News

  • US President Trump said on Friday that he will be hosting a state dinner for Chinese President Xi when he comes and that China has very little involvement with Iran.
  • China’s Finance Ministry announced it will lead a capital injection of CNY 360bln in state banks and insurers, with ICBC (601398 CH) planning to raise CNY 100bln to bolster its capital, and Agricultural Bank of China (601288 CH) to raise CNY 160bln through a private placement of A shares, while the insurers include China Life Insurance (601628 CH), China Taiping Insurance (966 HK) and People’s Insurance Company of China (601319 CH).
  • China unveiled a plan to strengthen rural investment and will boost rural revitalisation investments to boost agricultural productivity, while it will enhance bond and credit support for qualified agricultural initiatives.

European stocks were subdued and oil crept higher after tit-for-tat tanker strikes between the US and Iran. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. The Stoxx Europe 600 Index was little changed by 1:10 p.m. in London. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. 

Top European News

  • UK Chancellor Healey said Britain’s economic growth must extend beyond the largest cities as he prepares to outline his economic agenda in a major speech on Monday. He is reportedly to set to announce a GBP 150mln fund for northern firms, aiming to boost growth.
  • UK recruiters saw hiring pick up for the first time in four years in August, according to the FT citing a survey by KPMG and the Recruitment and Employment Confederation.
  • Hundreds of masked anti-immigration protesters blocked roads leading to Britain’s busiest ferry port in Dover on Saturday.
  • German Chancellor Merz warned about further losses of industrial jobs and said that they are losing industrial jobs on a large scale, although he welcomed the latest agreement on Volkswagen’s supervisory board.
  • Germany’s far-right AfD is set to win the election in the eastern German state of Saxony-Anhalt with 44.5% of the vote.
  • German police discovered 12 explosive devices near overhead powerlines in two districts in east Germany, which is the latest spate of incidents targeting Germany’s electricity infrastructure.
  • Greek PM Mitsotakis unveiled a package of economic measures including tax breaks and wage increases for pensioners and employees, with the measures costing EUR 3.5bln by 2030.
  • Fitch raised Portugal’s sovereign rating from A to A+; Outlook Stable.

Tariffs/trade

  • US President Trump said Canada’s dollar imbalance with the US is unacceptable.
  • US President Trump said on Friday that they have the right to put tariffs on nations like Switzerland and have the right not to trade with financial elite countries, while he also stated that he gets along very well with Mexico’s President.
  • Japanese Trade Minister Akazawa said progress was made on the USD 550bln investment initiative that was set up as part of a trade deal with the US.

FX

  • DXY struggled for direction after ultimately fading the knee-jerk uplift from the stronger-than-expected NFP report on Friday, with price action not helped amid the holiday closures in North America on Monday and with the Fed currently on a blackout period, while market participants will have to wait till much later in the week for US CPI data.
  • EUR/USD traded little changed just above the 1.1600 level, with the single currency unfazed by news that the German far-right AfD is set for a big election win in the eastern state of Saxony-Anhalt, but will fall short of achieving a majority. Separately, German Chancellor Merz warned about further losses of industrial jobs.
  • GBP/USD marginally softened although held on to the 1.3500 status, with participants looking ahead to comments from UK Chancellor Healey, who will outline his economic agenda in a speech today.
  • USD/JPY was range-bound on both sides of the 156.00 level in the absence of fresh catalysts from the US or Japan to begin the week, with both their central banks scheduled for key meetings next week.
  • Antipodeans conformed to the uneventful trade across the FX space amid the ultimately mixed risk appetite and with no tier-1 data to spur price action.
  • PBoC set USD/CNY mid-point at 6.7795 vs Exp. 6.7086 (prev. 6.7787)

Fixed Income

  • 10yr UST futures lacked direction after whipsawing in the aftermath of last Friday’s blockbuster jobs report, while price action is contained with US cash markets closed on Monday for Labor Day.
  • Bund futures trickled lower and returned to beneath the 123.00 level amid mild gains in oil prices and with German Industrial Production data due later, while there was little impact from news that Germany’s far-right was set for a major victory after elections in the eastern state of Saxony-Anhalt.
  • 10yr JGB futures were subdued in the absence of any major fresh drivers or tier-1 data from Japan.

Commodities

  • Crude futures mildly gained after the US and Iran conducted tit-for-tat attacks on vessels in the Strait of Hormuz during the weekend, but with upside capped as it was also reported that Iran’s top security official Rezaei said Tehran will declare a restricted zone near the Strait of Hormuz and announce a new shipping route agreed on with Oman in the coming days and weeks.
  • Major OPEC+ countries stuck with the plan to keep oil output quotas unchanged for October.
  • Iraq raised oil export capacity to over 3mln bpd, according to state media.
  • US Energy Secretary Wright said the Trump administration is focused on boosting crude and fuel supplies rather than curbing US exports, as a way to reduce prices. Wright also said that US Navy escorts that are assisting tankers across the Strait of Hormuz are vital in sustaining crude flows and suggested they will continue to do so until Iran backs down.
  • Russia’s Vostok Oil project loaded its first crude for shipment via the Northern Sea route.
  • Iran is to increase gasoline prices for heavy consumers using more than 110 litres per month, effective on Tuesday.
  • Spot gold retested the USD 4,400/oz level to the downside following last week’s stronger-than-expected US jobs data, which supports the case for the Fed to hike rates this month.
  • Copper futures ultimately declined with early indecision on the recent key market themes including US data, Fed rate expectations and ongoing geopolitical tensions.

Geopolitics: Ukraine

  • Ukrainian President Zelensky sees no quick end to the war with Russia following a meeting with US envoys Witkoff and Kushner, and is seeking a package from allies that would cover defence reinforcements, as well as energy, including US LNG.
  • Russian President Putin ordered troops not to fire on Kyiv for three days during US envoys Witkoff and Kushner’s visit to Ukraine’s capital, according to Kremlin spokesman Peskov. However, it was reported that Russia and Ukraine exchanged a wave of strikes prior to the US envoys’ visit to Kyiv.
  • Russian Kremlin aide said talks between Russia and the US were highly useful and lasted for over three hours, but gave no indication of a breakthrough.
  • White House official said US and Russian officials discussed substantive plans for the next steps in talks aimed at ending Russia’s war in Ukraine, which will be announced in the coming weeks.
  • France’s far-right National Rally chief Bardella wants Ukraine to pay for Europe’s help and said France’s unconditional support for Ukraine should be replaced by a more transactional relationship.

Geopolitics: Other

  • North Korean leader Kim said North Korea’s navy nuclear armament will put nuclear combat systems to practical use and will restrain the enemy’s invading fleet, while he added that their new warship can carry out annihilating retaliatory strikes on the enemy at any time.

DB’s Jim Reid concludes the overnight wrap

Morning all. Tough times in our house this weekend with 8 nine-year-old boys sleeping over for our twin’s birthday party. They were very noisy. However, we were kept awake not by them but by an illegal rave in a field a few hundred yards away. I say we but my hearing isn’t the best so I didn’t hear it. My wife has the hearing of an owl and couldn’t sleep through it and felt that I should be woken up to be made aware of the noise I couldn’t hear. So I could do with the weekend to start again. Thankfully it’s US Labor Day so it should be relatively quiet.  

I was asked to do an op-ed for the FT today on the recent yield sell-off in bond market. As I said in the piece, the moves over the summer are just another leg to the normalisation trade that has been going on post Covid. In the unlikely event that you’d been on a desert island since just before the GFC and came back ashore today, I’m sure you’d look at current yields as pretty normal given all the spot info and history of bond markets you had at your disposal. I also don’t think the recent concerns are fiscal related, even if the higher yields go the more worries we will have further down the line for several countries. Finally while the pressures that have been there for higher yields are likely to continue, we have to accept that bonds are being bonds again. That is the coupon is helping maintain returns even in the face of yield rises. For example, its been nearly 4 years since the UK mini-budget crisis and 10yr Gilt yields are +65bps than the peak, while index returns are up around 12%. Clearly not spectacular but its getting harder to get outright negative returns in government bonds over the medium-term. So while the news flow will likely to continue to be negative, at least bonds are being bonds again. See my op-ed at the FT here for more. 

The main headline this morning is Germany’s political landscape shifting further to the right after the AfD secured around 44% of the vote in the Saxony-Anhalt state election yesterday, its strongest result in any German election to date and more than double its support from 2021. Chancellor Friedrich Merz’s CDU slumped to roughly 17%, its weakest showing in the state, as voters expressed growing frustration over economic stagnation, energy costs and migration policy. While the AfD fell just short of an outright parliamentary majority, the result nonetheless marks a major symbolic breakthrough for a party that remains shunned by mainstream rivals under Germany’s long-standing political “firewall”. The outcome will intensify pressure on the federal government and is likely to reinforce concerns about political fragmentation. More broadly, it underlines how anti-establishment and populist parties continue to gain traction across parts of Europe despite robust labour markets and relatively subdued inflation.  

The main focus in the Iran conflict over the weekend was a tit-for-tat escalation targeting commercial shipping in and around the Gulf. According to Reuters and other major news agencies, several tanker incidents and maritime attacks heightened concerns about the security of energy supplies moving through the Strait of Hormuz, with both sides accusing each other of responsibility. Brent is up +1.05% this morning to $97.29/bbl so we remain a distance from a resolution.

Elsewhere in overnight markets, tech is lifting most boats with the KOSPI (+4.18%) leading gains, followed by the Nikkei (+1.87%). Chinese equities are mixed, with the CSI 300 (+0.19%) edging higher, while the Hang Seng (-0.97%) and Shanghai Composite (-0.34%) are underperforming and bucking the broader regional trend. S&P 500 futures (-0.11%) are trading slightly lower but activity will be light today due to the Labor Day holiday. The Yen is fairly flat after another hectic week of intervention stories.

Looking forward now and the coming week offers a busy mix of central bank decisions, inflation data and growth indicators across the major economies. The main global focus will undoubtedly be on the US inflation reports (including CPI on Friday) and the ECB policy meeting (Thursday) with the former likely to heavily influence the FOMC next week. Elsewhere, investors will look to China’s trade (tomorrow) and inflation data (Wednesday), UK monthly GDP (Friday), and industrial production releases in Germany (today) and France (Wednesday). Corporate earnings are relatively light but Oracle (Thursday), Adobe and Inditex are among the notable releases.
As noted above, the biggest event is likely to be the US August CPI report (Friday), arriving just days before the September 16 FOMC meeting. The release follows a stronger-than-expected August employment report last Friday that reinforced the view that the labour market remains resilient. Nonfarm payrolls rose by 162k, with a further 55k of upward revisions to the previous two months. Private-sector hiring remained firm (127k) and job gains continued to broaden beyond healthcare, while measures of labour demand improved further.

Although the unemployment rate edged up to 4.14%, the broader U-6 measure fell to 7.7% and participation increased to 61.6%, suggesting the labour market remains on a relatively stable footing. Overall, the report corrected some of the softer signals seen in July and supports the view that employment growth remains at or slightly above breakeven levels.

Attention now turns to inflation. Our US economists expect headline CPI (Friday) to rise by +0.38% month-on-month in August, up from +0.07% previously, while core CPI is expected to print at +0.21% month-on-month, broadly unchanged from July’s +0.22%. Higher gasoline prices are likely to support the headline reading, while core inflation should continue to benefit from gradually moderating shelter costs. If realised, the forecasts would leave headline CPI broadly unchanged at 3.38% on a year-on-year basis while core inflation edges 10 bps lower to 2.38%.

Ahead of that, the PPI (Thursday) will provide another important input into the inflation outlook. Our US economists expect PPI to imply a +0.21% month-on-month increase in core PCE, down from +0.25% in July, leaving the annual rate broadly stable. The remainder of the US calendar is relatively quiet, with markets closed today for the Labor Day holiday. However, the preliminary University of Michigan consumer sentiment survey (Friday) will also attract attention. Our US economists expect sentiment to improve to 52.5 from 51.7 in August, while the survey’s inflation expectations measures will be closely watched.

In Europe, the ECB policy decision (Thursday) will be the key event. Our European economists expect a 25bp rate increase, taking the deposit rate to 2.50%, and investors will focus on any guidance regarding the likelihood of further tightening. Our economists now expect an additional hike in December with the reasons explained in their preview note here. They have also upgraded their 2026 and 2027 economic forecasts by 0.3pp and 0.1pp to 0.8% and 1.2% respectively. See their note on it here.  Economic data will also be closely monitored, including German industrial production (today) and trade data (tomorrow), French industrial production (Wednesday), and UK monthly GDP (Friday). Inflation releases from Sweden (today) and Norway and Denmark (Thursday) will provide additional insight into regional price pressures.

In Asia, China will dominate the calendar. Our economists expect the August trade balance (tomorrow) to show stronger activity, with exports and imports forecast to grow a significant 27% and 29% year-on-year respectively. Inflation data (Wednesday) are expected to show CPI accelerating to 0.8% year-on-year from 0.5%, while PPI inflation moderates to 3.2% from 3.5%. In Japan, key releases include labour cash earnings and the Economy Watchers survey (tomorrow), followed by PPI data (Friday).  A reminder that the BoJ has an important meeting on Friday week, less than 36 hours after the FOMC conclusion.

Beyond the economic calendar, the US Treasury’s expanded long-end buyback programme begins on Wednesday, increasing support operations in longer-dated maturities. In politics, the US Republican Party will hold its first midterm national convention in Dallas on Wednesday and Thursday, while Canada’s counter-tariffs on US imports come into force tomorrow. Corporate earnings highlights include Inditex (Wednesday) and Adobe and Oracle (Thursday). Oracle will be the key given all the focus on AI capex.  

Recapping last week now and risk assets struggled to gain much traction, as a fresh rise in energy prices raised fears about more persistent inflation. That came amidst no signs of progress on reopening the Strait of Hormuz, with Brent crude oil up +7.80% last week (+0.80% Friday) to $96.28/bbl, their highest in six weeks. Moreover, the relentless rise in European natural gas futures continued, with a 4th consecutive weekly gain (+7.42%) last week (+0.20% Friday) to €72.00/MWh. So for Europe in particular, investors were pricing in a growing probability of a more inflationary shock.   

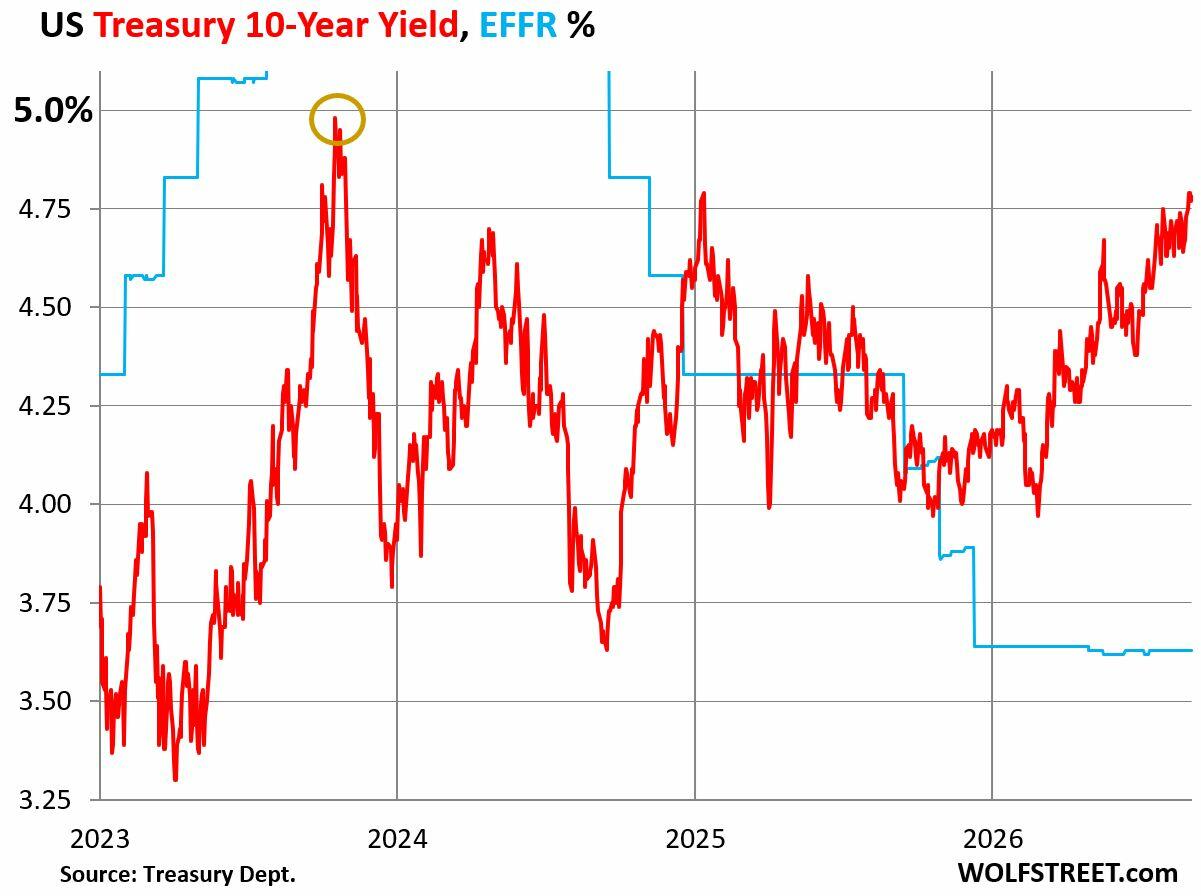
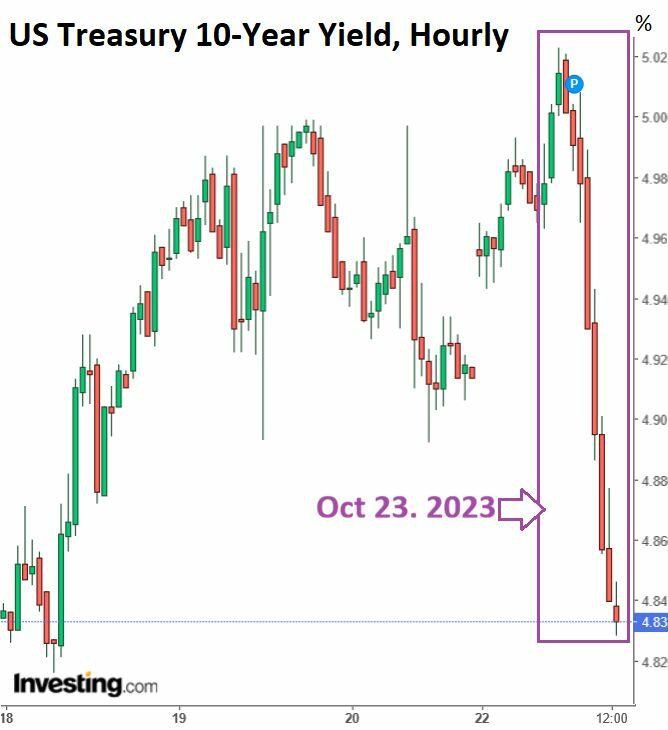
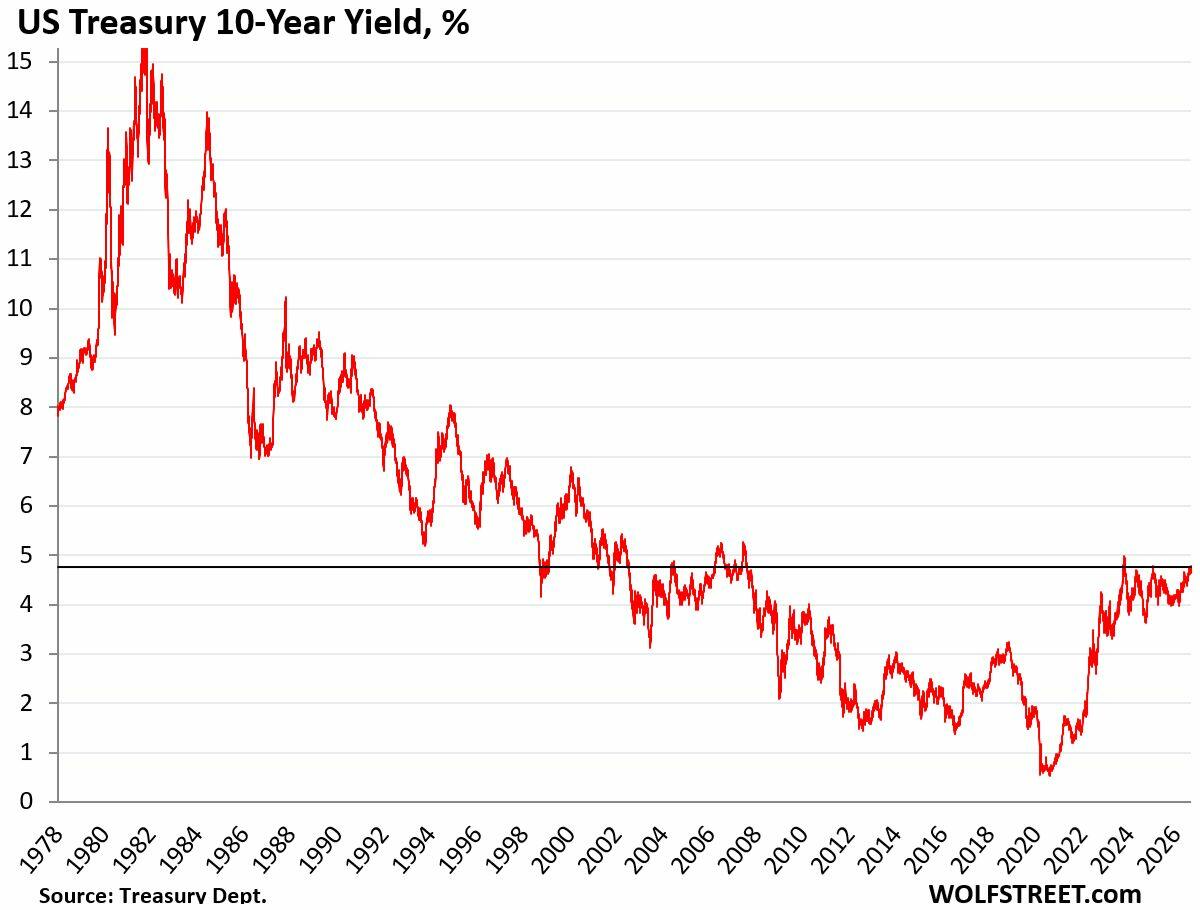
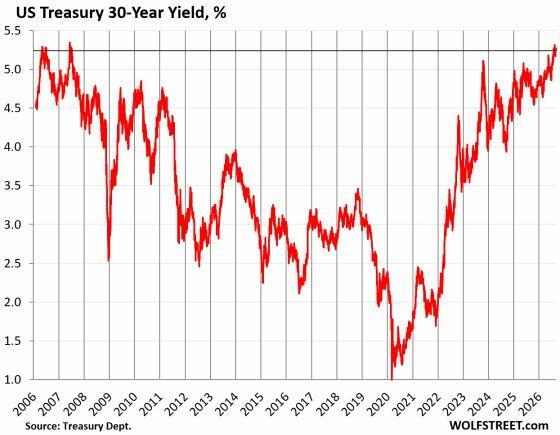
That backdrop helped push yields up to multi-year highs around the world. For instance in Germany, the 10yr bund yield was up +6.1bps last week (-0.4bps Friday) to 3.34%, and it even reached a post-2011 high of 3.37% on Wednesday. Meanwhile in the US, the 10yr yield was up +6.3bps last week (+1.4bps Friday) to 4.78%, and on Tuesday it closed at 4.80%, its highest since October 2023.   
The yield moves got further momentum on Friday from a very strong US jobs report, which showed payrolls up by +162k in August (vs. +55k expected). In addition, there were +55k of upward revisions to the previous two months, and the unemployment rate held steady at 4.1%. So that raised investors’ confidence that the Fed would likely hike rates at their September meeting, with futures pricing in a 62% chance of a hike by the close on Friday.   

With inflationary pressures mounting and yields rising further, that generally put pressure on risk assets around the world. That was particularly clear in Europe, where the STOXX 600 fell -0.81% last week (+0.12% Friday), whilst the DAX fell -1.97% (+0.17% Friday). Elsewhere, Japan’s Nikkei also fell -2.09% (+1.26% Friday), while the MSCI EM index rose +0.24% (+1.35% Friday). In the US, equities saw a relative outperformance, but even there, the S&P 500 was still barely up last week with a +0.09% gain (-0.38% Friday). That slight risk-off tone was seen in credit as well, as US IG (+2bps) and HY (+7bps) spreads both widened, as did Euro IG (+2bps) and HY (+8bps) spreads.

Tyler Durden
Mon, 09/07/2026 – 09:22

via ZeroHedge News https://ift.tt/awBbj9V Tyler Durden

Central Banks Bought 23 Tonnes Of Gold In July

Central Banks Bought 23 Tonnes Of Gold In July

Authored by Naveen Athrappully via The Epoch Times,

Central banks worldwide purchased a net 23 tonnes of gold in July, in line with the overall yearly trend, according to the World Gold Council (WGC).

Gold bars weighing 1000 grams each are displayed at the Austrian Gold and Silver Refinery (Oegussa) in Vienna, Austria, on Feb. 3, 2026. Georg Hochmuth/APA/AFP via Getty Images

The largest buyer last month was China, which bought 20 tonnes, according to a Sept. 3 WGC report.

“Notably, activity from the People’s Bank of China (PBoC) has picked up pace in recent months, with double-digit monthly purchases of gold since May 2026,” the report said. Poland purchased eight tonnes and was the second-largest buyer.

Russia was the top net seller, with six tonnes sold. This was followed by Turkey, Uzbekistan, and Jordan, all of which sold a tonne each.

Year-to-date, global central banks reported purchasing 130 tonnes of gold, down from roughly 160 tonnes during the same period in 2025. Poland has added 90 tonnes this year, with China buying 60 tonnes. Turkey has sold 85 tonnes, while Russia’s sales total 50 tonnes.

Central banks account for roughly 20 percent of all historically mined gold, according to the WGC. Bullion serves as a vital bank reserve asset, valued for its liquidity, safety, and potential returns. In times of uncertainty, gold demand tends to rise.

According to a June 16 WGC report, a survey of central banks found that 89 percent of respondents forecast global central bank gold reserves to rise over the year.

As for funding, half of the respondents said they would procure the gold locally by using domestic currencies. Thirty-eight percent said they would sell other reserve assets to purchase gold.

“The majority of respondents (74 percent) see moderate or significantly lower US dollar holdings within global reserves over the next five years,” the report said.

“Respondents also believe that the share of other currencies, such as the euro and renminbi, will remain unchanged over the same period, while gold holdings will increase.”

Goldman Sachs predicts central bank buying will support the rise in gold prices, according to an Aug. 28 report. Such purchases are being driven by a need to diversify their reserves.

In 2022, the G7 nations froze Russia’s assets held in Europe due to Moscow’s invasion of Ukraine. Since then, the central banks have been buying gold at an increased rate, according to Goldman Sachs.

Spot gold ended Friday at around $4,430 per oz., up from about $4,329 at the beginning of the year. Gold hit a peak of roughly $5,595 in late January.

Unable to Withdraw Gold

The Sept. 3 WGC report cites a conflict between Venezuela and the Bank of England over gold reserves.

The Venezuelan government has roughly $4 billion worth of gold stored with the bank and has sought to withdraw it. However, because the United Kingdom has refused to recognize Venezuela’s socialist government, the country has been unable to secure its gold reserves.

According to the June 16 WGC report, central banks are continuing to diversify the locations of their gold reserves. While the Bank of England remained the top choice, domestic storage was a close second, followed by the Bank for International Settlements in third place.

This week, the Netherlands’ central bank announced plans to shift roughly 86 tonnes of gold from the United States and Canada to London, citing geopolitical risk.

Ewa Manthey, commodities strategist at ING Bank, highlighted the risk faced by certain nations that store gold abroad, citing Venezuela’s inability to retrieve its gold from the Bank of England, according to a Sept. 4 opinion on the company’s website.

“This case is exceptional – but it shows that the host country’s courts and political recognition decisions can affect access to reserves,” Manthey said.

“Gold held at the Bank of England remains the property of the foreign central bank, but it is physically located in the UK and is therefore subject to UK jurisdiction.”

Tyler Durden
Mon, 09/07/2026 – 09:15

via ZeroHedge News https://ift.tt/SNjiIw3 Tyler Durden

New York Rediscovers Nuclear Power, With Plenty Of Political Fine Print

New York Rediscovers Nuclear Power, With Plenty Of Political Fine Print

Five years after Indian Point’s last reactor shut down, Albany rediscovered the appeal of electricity that runs around the clock without burning fossil fuels.

Governor Kathy Hochul wants 5 gigawatts of new nuclear capacity, with at least 1 GW developed by the publicly owned New York Power Authority, plus a separate 4 GW initiative. 

There haven’t been any announcements for the technology of choice, but the most likely candidates are the large Westinghouse AP1000 and the smaller 300 MW BWRX-300 from GE Vernova Hitachi.

As Canary Media reports, the reversal follows this spring’s weakening of New York’s climate law. The state’s difficulties with delivering large renewable projects also hasn’t helped keep them on the pure-play renewables path, which was made worse with the Trump administration’s assault on offshore wind.

The construction of new nuclear power generation offers a governor facing re-election a unique win-win opportunity: nuclear offers dependable low-carbon generation alongside renewables while also offering industrial investment, construction jobs and promises of lower bills.

Eight upstate communities have expressed interest in hosting projects. With strongly Republican-leaning counties on the list of possibilities, including Jefferson, Oswego, and Schuyler, Gov. Hochul could use the new mega-projects to score political points.

NYISO’s 2026 Power Trends warns in their recent report that trying to replace over 4 GW of something that’s almost always on (nuclear) with less than 3 GW of something that’s almost always off (renewables) isn’t exactly how you set the state up for future success.

The report from NYISO does highlight a common problem between nuclear and other sources of generation, which is the issue of actually getting the power where it needs to go. If most of the energy demand is downstate, then additional dependencies and bottlenecks come into play. Transmission capacity becomes a problem to get the power from upstate.

Then there is Indian Point. As we previously reported, Energy Secretary Chris Wright has pushed to revive the roughly 2 GW facility, whose retirement increased reliance on fossil generation. Hochul opposes reopening it while championing new construction upstate.

A restart would require substantial work, however, a precedent is already being set with other restarts around the country, most notably at the Palisades. If there is true concern in the state for meeting baseload needs, then outright rejecting the restart of a nuclear facility becomes confusing.

Opponents are arguing nuclear spending could crowd out faster alternatives, so Senator Kevin Parker’s pending legislation would impose a 30-month pause on taxpayer and ratepayer support for new or restarted nuclear facilities while a task force studies costs and alternatives.

As we have highlighted a few times now, selective nuclear enthusiasm extends well beyond Albany.

Texas committed $350 million to advanced nuclear development in 2025. Yet Greg Abbott fought the proposed Andrews County spent-fuel storage facility, and Texas enacted restrictions in 2021 on offsite high-level waste storage.

New Mexico similarly committed almost $5 million in development assistance and workforce support for Kairos Power’s Albuquerque expansion. Meanwhile, state officials battled Holtec’s proposed HI-STORE spent-fuel facility. Holtec abandoned the New Mexico project in 2025.

The common thread is an appetite for nuclear generation capacity accompanied by arguments over who carries the liabilities. New York’s pivot could strengthen its grid for decades, potentially even the next century, if it can follow through with its swing.

Tyler Durden
Mon, 09/07/2026 – 08:30

via ZeroHedge News https://ift.tt/qSuF8dH Tyler Durden

The 10-Year Treasury Yield Over 5%? Some Thoughts

The 10-Year Treasury Yield Over 5%? Some Thoughts

Authored by Wolf Richter via WolfStreet.com,

The 10-year Treasury yield has been zigzagging higher since mid-November when the Fed cut its policy rates again despite accelerating inflation. Since that rate cut, followed up by another rate cut in December, the 10-year yield has risen by 80 basis points, heading, apparently inexorably, for the 5%-line.

On Friday, it closed at 4.78%, within spitting distance of 5%, despite Bessent’s three hocus-pocus shows to try to bring it down. Sure, they might have helped keeping a lid on long-term yields, as Bessent pointed out; who knows where the 10-year yield would be by now without the hocus-pocus shows. Maybe already over 5%?

The 10-year yield is now 115 basis points above the Effective Federal Funds Rate (EFFR, blue line), which the Fed targets with its policy rates. Note the November rate cut – the drop in the blue line – despite accelerating inflation. That’s when the zigzag higher began.

Buyers and sellers in the bond market have good reasons for pushing up the 10-year yield: Inflation refuses to go back into the bottle. The Fed refuses to force inflation back into the bottle, triggering loose financial conditions in most areas of the economy, except in real estate. And the government refuses to even entertain a modicum of spending cuts and tax hikes to contain the deficits. It’s been the opposite: tax cuts and spending hikes, and they’re still talking in those terms.

The government’s unwillingness to contain the deficit causes a flood of supply of new debt needed to fund the deficits. The bond market has to absorb that new debt by luring in new buyers with higher yields – investors that are now sitting on the sidelines watching this play out. If yields move high enough, these investors will begin to nibble, and if yields move higher still, these investors will nibble some more, and if yields move a lot higher still, investors might take big bites. Some of those investors have been nibbling, but the supply keeps coming, and so the 10-year yield keeps rising.

Those reasons for pushing the 10-year yield higher aren’t going away anytime soon as neither the Fed nor the government is willing to do what it takes.

The 10-year yield had already breached the 5%-line for a few moments intraday on October 23, 2023, but that was too fast too soon, after a massive surge of 170 basis points in six months. And at 5%, the nibblers started taking out huge bites, and the sellers stopped selling, with the spectacular effect that the yield plunged by 19 basis points intraday, from 5.02% to 4.83%.

That day is circled in the chart above, showing only the closing yields. The yield then continued to plunge for the next two months, and that’s how that run for 5% ended.

Here is the hourly spectacle on October 23, 2023:

A 10-year Treasury yield above 5% and well-above 5%, was essentially the norm in the decades before 2008, before QE. Between the mid-1960s and the Dotcom Bust recession, the 10-year yield was nearly always higher than 5%, going as high as 15%. So 5% isn’t anything unusual or unheard of. For several decades, it used to be considered low.

The exception occurred during the Dotcom Bust that was hitting the economy, to which the Fed responded by cutting its policy rates as low as 1%, and kept them there too long, causing Housing Bubble 1 to bloom, which ended in the Housing Bust, which triggered the mortgage crisis, which triggered the Financial Crisis. During that time, starting in June 2002 through April 2006, the 10-year yield dropped below 5%, and stayed mostly below 5%, and for part of the time even below 4%. Then it went back over 5% again, when the Housing Bust and the Fed’s reaction to the budding Financial Crisis pushed the yield back below 5%. But it didn’t drop below 4% until the Fed started QE in 2008.

The 30-year Treasury yield hasn’t been so constrained by an imaginary line that formed some kind of ceiling, where the masses come out and buy. It has zigzagged past its October 23, 2023 high, to a two-decade high. On Friday, it closed at 5.24%.

The 10-year Treasury yield looks like it wants to break out – it looks like it already made the first step to breaking out, by leaving behind its two-month range from 4.62% to 4.72%. At some point, sooner or later, given the history of the 10-year yield, the buyers and sellers in the bond market will make another run at 5%.

The big question that arises is this: Will the same thing that happened on October 23, 2023, happen all over again, when huge demand suddenly comes off the fence at that long-awaited 5%, while sellers, shocked and appalled, pull back, thereby causing the yield to plunge again?

Or will the 10-year yield blow through the 5% – with fretting sellers burning through the worried and careful buyers – and head higher, and remain above 5%?

The government’s fiscal policies are asking for it. The Fed’s policies of being soft on inflation are asking for it. The $40 trillion in Treasury debt outstanding is asking for it.

A 10-year yield of 5%+ is obviously not the end of the world. The US economy has done fine with a 5%+ yield, including during the Dotcom Bubble, which generated a very tight labor market, big pay increases, and lots of economic growth despite a 10-year yield mostly in the range between 5-8%.

And the ratio of interest payments to tax receipts that are available to pay for them was much higher from the mid-1980s through the mid-1990s (see my analysis: Quarterly Update on the Ugly Fiscal Condition of the US in Q2 2026).

Tyler Durden
Mon, 09/07/2026 – 08:10

via ZeroHedge News https://ift.tt/GlHAidJ Tyler Durden