Federal Court Allows Libel-by-AI Claim (Brought by Protagonist of Apple TV’s Black Bird Series) to Go Forward

From today’s decision by Judge Thomas Durkin (N.D. Ill.) in Keene v. Google LLC:

Keene is an author, television producer, and former FBI operative. In 1997, he pled guilty to conspiracy to distribute drugs and was sentenced to ten years in prison. In exchange for a pardon, Keene agreed to work with the FBI as a prison informant to help gather evidence against suspected serial killer Larry Hall. Hall was ultimately convicted, and Keene’s conviction was expunged. Keene published a memoir recounting this experience that was subsequently adapted into an Apple TV miniseries titled “Black Bird.”

Keene alleged that, from May 24 to June 27, 2025, at least four Google “AI Overviews” said false things about him:

  1. Keene was “serving a life sentence without parole for multiple convictions.”
  2. He was “serving a life sentence without parole for the murders of three women.”
  3. He “was convicted of drug trafficking.”
  4. He was “serving a life sentence without parole in Butner, North Carolina.”

The first three overviews were allegedly responses to a search for “Jimmy Keene net worth,” and the fourth to a search for “Is Jimmy Keene still alive.”

Each AI Overview cited a Wikipedia page as the source of the information and provided a link to that page. However, the Wikipedia page did not contain the false statements in the AI Overviews. AI Overviews 1 and 2 were seen by various family members, friends, and acquaintances.

Keene complained to Google about the false statements on three occasions: May 27, 2025, May 31, 2025, and after June 27, 2025. Google allegedly apologized to Keene after each complaint and deemed the statements errors made by its Artificial Intelligence.

Keene sued, and the court allowed the case to go forward as to AI Overviews 1, 2, and 4 (with one minor procedural twist as to AI Overview 4 that I’ll mention below). The court held that Keene had sufficiently alleged that an ordinary reader would have understood the statements as factual assertions:

First, Google argues that its standard disclaimer indicates that AI Overviews are merely “starting points” using rapidly evolving technology and not statements of fact. According to Google, a disclaimer appears along with all AI Overviews warning that AI Overviews “may include mistakes.” However, the disclaimer Google references is not identified in the Complaint nor included in the attached exhibits. Indeed, Keene maintains that additional “test” Google searches conducted by his counsel did not include any such disclaimer.

Whether or not a disclaimer was present is a factual dispute not to be determined at this stage. In ruling on a motion to dismiss, the Court must accept all well-pleaded facts as true and draw all reasonable inferences in Keene’s favor. Therefore, the Court’s analysis proceeds without consideration of an alleged disclaimer.

Second, Google argues that users could easily verify that the AI Overviews contain false information based on the linked Wikipedia article or other search results. But Google’s cited cases do not support that merely linking to a source with correct information vitiates defamation….

Google also cites Walters v. Openai, L.L.C. (Ga. Super. 2025), in which a journalist asked ChatGPT, an AI large language model (“LLM”), to summarize a legal document. The journalist intentionally sought out an LLM, had prior experiences when the LLM provided him “flat-out fictional responses,” assented to an acknowledgement that responses may include “incorrect Output,” reviewed multiple disclaimers regarding the potential for information that could be “misleading” or “inaccurate,” and received responses stating that the LLM could not provide the desired information. The court granted summary judgment in favor of the defendant in part because a reasonable reader in the journalist’s position “could not have concluded that the challenged ChatGPT output communicated ‘actual facts.'”

Google’s reliance on Walters is unpersuasive because the context in the instant case is wholly distinct. From the perspective of an ordinary user, asking an AI LLM to generate work product and receiving numerous indicia of falsity is different from a basic Google search.

In Google’s own words, a Google search is meant to “connect a user most efficiently to relevant and reliable information.” Although Google has now developed its own built-in AI LLM to “enhance” a search by summarizing information, an ordinary user searching “Jimmy Keene net worth” on Google is seeking factual information, not AI work product. Only after a user read the linked Wikipedia article would any contradiction become apparent, but without reason to question the AI Overviews, many ordinary users would not conduct that further research.

Google asserts that AI Overviews are just the “starting point” for users to “dig deeper.” To the contrary, factual statements with citations to outside sources provide contextual support that the AI Overviews are summarizing objectively verifiable facts contained therein and additional research is not required.

“If it is plain that the speaker is expressing a subjective view, an interpretation, a theory, conjecture, or surmise, rather than claiming to be in possession of objectively verifiable facts, the statement is not actionable.” But that is not the case here. By pointing out that the statements in the AI Overviews are objectively verifiable, Google concedes the very point it is arguing against—the statements are facts….

Keene didn’t dispute that he was “a limited public figure regarding commentary on his own life’s story,” which meant that he had to adequately allege “actual malice,” which is to say knowing or reckless disregard of falsity. But the court said this requirement was satisfied:

Probative evidence of recklessness includes a publisher’s knowledge of serious factual inconsistencies, as well as the failure to investigate or independently verify disputed or questionable factual assertions.

Keene contends that he has sufficiently pled actual malice because he directly notified Google on three occasions that it was publishing false information about him. Despite this notice, Google continued to publish similar defamatory statements through at least late June 2025. Keene further alleges that Google repeatedly acknowledged and apologized for the false AI Overviews appearing on its platform, thereby admitting awareness of their existence, yet continued to permit their publication with actual knowledge of their falsity or at minimum reckless disregard for their truth.

Google argues that Keene has not adequately pled actual malice because Keene’s allegations are conclusory and he does not allege that he informed the individuals at Google responsible for publishing the AI Overviews about their alleged falsity. See N.Y. Times Co. v. Sullivan (1964) (stating that a plaintiff must “br[ing] home” the state of mind required for actual malice “to the persons in the … organization having responsibility for the publication”). But Keene pleads that he corresponded with Google multiple times regarding the false statements contained in the AI Overviews. Prior to discovery, Keene may not know the names of the responding individuals. But at this stage, allegations of correspondence plausibly indicate that such emails were circulated to individuals at Google responsible for policing the AI Overviews, who then, with knowledge of falsity of the AI Overviews, took no corrective action and the statements continued to be published.

Google also attempts to introduce emails to discredit claims that Google acknowledged and apologized to Keene. However, the introduction of such evidence is not pertinent at the pleading stage. Even if the Court considered the emails, while they do not support the allegations of repeated apologies, they do support that Keene repeatedly alerted Google that the AI Overviews could be defamatory.

Google’s Exhibit 3 shows that Keene filled out and submitted a form to “report a legal removal issue” to Google on May 25, 2025, which described in detail his complaints concerning the AI Overviews. Either this report made its way to an individual at Google, which could plausibly support actual knowledge of falsity, or no human at Google reviewed the legal removal request and subsequent correspondence, which could plausibly support reckless disregard for falsity. Without more information, the emails are not dispositive. At this stage, the Court need only determine whether Keene has plausibly alleged actual malice. He has.

The court noted that Keene had failed to “plausibly allege publication to a third party” as to AI Overview 4, which Keene said was a “mere clerical oversi[ght]” in drafting the complaint. Because of this, the court dismissed the claim as to Overview 4, but allowed Keene to amend the complaint to resolve that problem.

The court held, though, that AI Overview 3 was substantially true and therefore wasn’t defamatory:

AI Overview 3 states that Keene “was convicted of drug trafficking.” In fact, Keene was convicted of felony conspiracy to distribute cocaine…. “[D]rug trafficking” is a term in common usage that encompasses drug distribution often as part of a larger enterprise…. [And t]he fact that Keene’s conviction was later expunged does not negate substantial veracity.

For more on other such recent lawsuits, see my Large Libel Models posts; for more on the legal issue, see Large Libel Models? Liability for AI Output.

Jeffrey B. Steinback and T. Paul S Chawla represent Keene.

The post Federal Court Allows Libel-by-AI Claim (Brought by Protagonist of Apple TV's <i>Black Bird</i> Series) to Go Forward appeared first on Reason Magazine.

from Latest – Reason Magazine https://ift.tt/EQ0Lste
via IFTTT
Trump Declares Ukraine, Russia Have Agreed To Halt All Attacks On Energy Targets

Trump Declares Ukraine, Russia Have Agreed To Halt All Attacks On Energy Targets

Update(11:19)ET: Amid soaring national diesel products and painfully high prices at the pump, President Trump on Monday announced the Zelensky government has acceded to the US president’s prior call to abstain from attacking diesel infrastructure in Russia. He has unveiled what he’s presenting as a new Russia-Ukraine energy ceasefire.

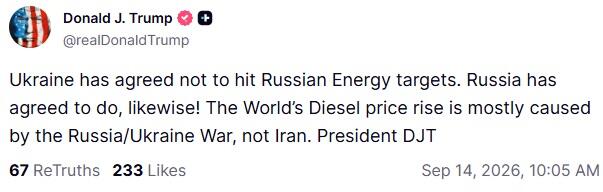
Trump says “Ukraine has agreed not to hit Russian Energy targets. Russia has agreed to do, likewise! The World’s Diesel price rise is mostly caused by the Russia/ Ukraine War, not Iran.” Clearly high fuel prices are creating immense pressure within the GOP, and Trump is trying to essentially tweet his way out of this war-related mess…

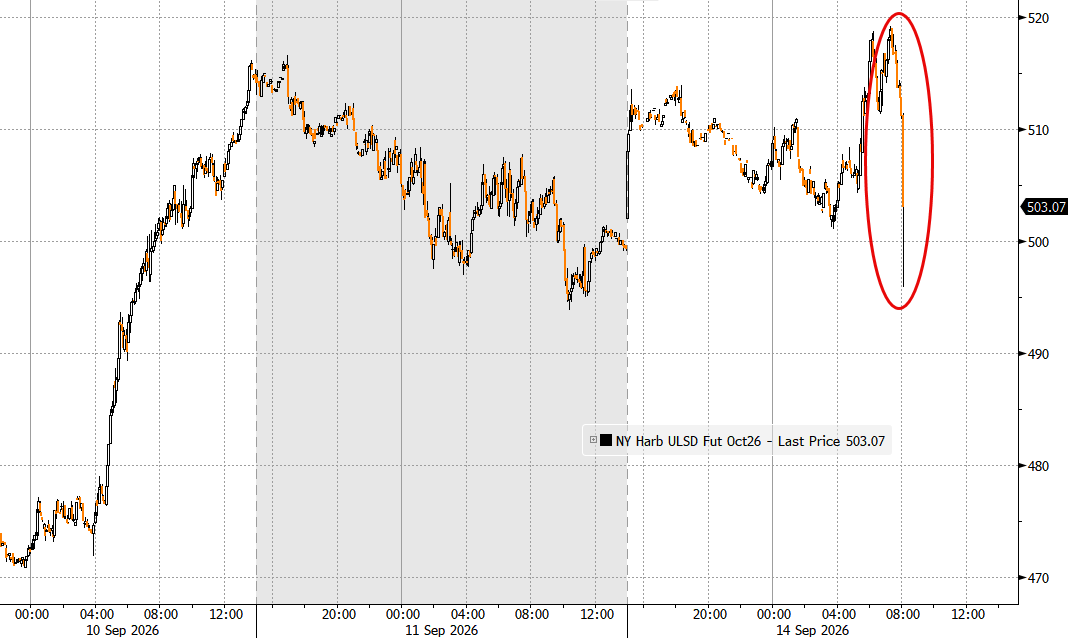
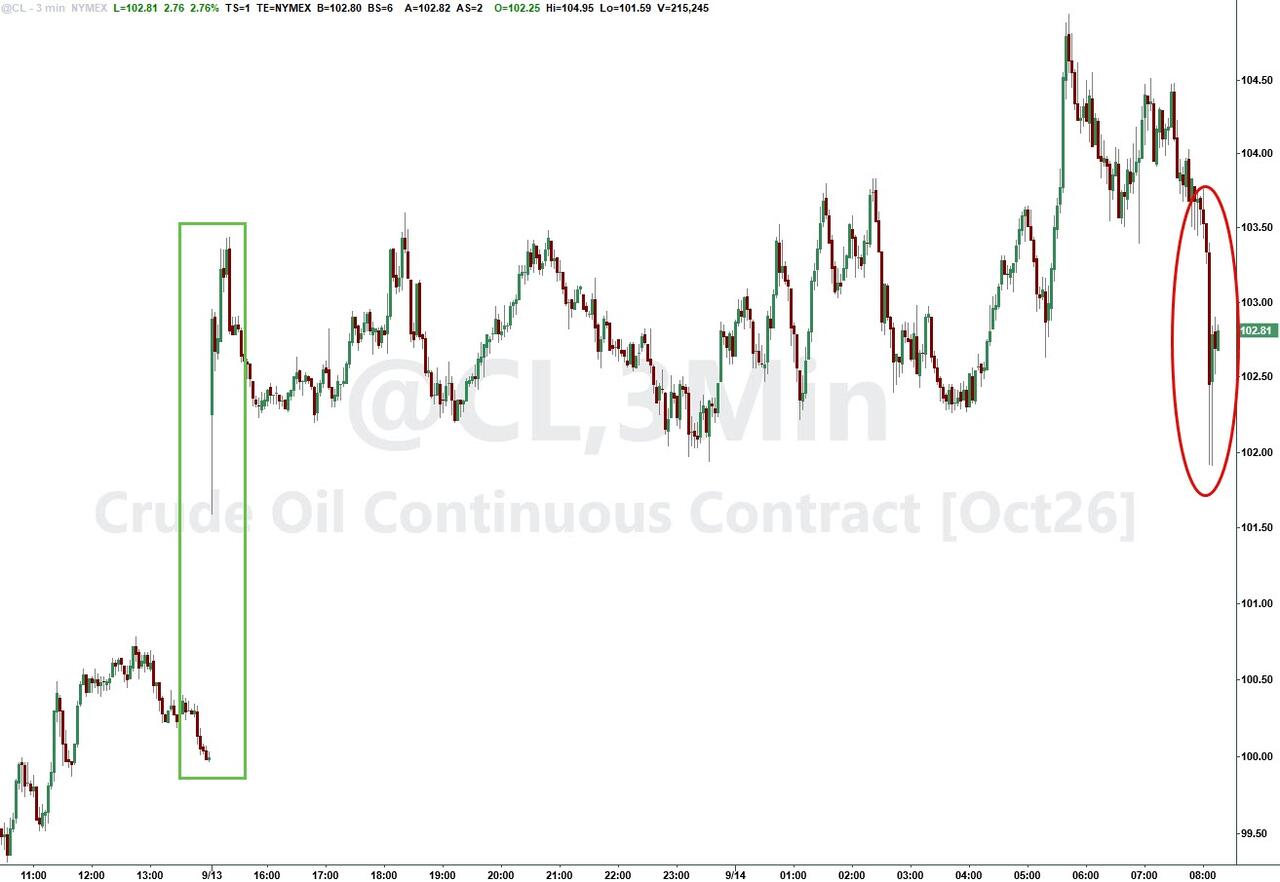
DIESEL FUTURES PARE GAINS, TRADE NEAR $5.04/GAL

Diesel responded immediately…

And also crude…

*  *  *

The Kremlin has welcomed President Trump’s weekend call for Ukraine to stop attacking Russian diesel supply and infrastructure sites. The somewhat surprise remarks which will only serve to further pressure the Zelensky government came when pressed by a reporter on Sunday. Trump responded by saying Zelensky “has to do one thing. He has to stop knocking out diesel fuel in Russia.”

The US president said at the sidelines of the Irish Open on Sunday, “There are plenty of other targets. Don’t hit diesel fuel, because that’s hurting, that’s hurting the world” – adding that he indeed had spoken to the Ukrainian president about it.

“I’ve asked Zelensky not to hit the Russian refineries. Diesel is being driven up by the fact that it’s having a hard time coming out of Russia,” Trump additionally stated. “That’s a case that hurts the world, and we’ve got to stop it.”

On Monday, Putin spokesman Dmitry Peskov was asked about Trump’s words. “Of course, one can only welcome any call on the Kiev regime to stop strikes on civilian economic infrastructure, Peskov told a press briefing.

via Associated Press

The Kremlin official had been questioned on whether Putin views the US call to refrain from strikes on Russia’s diesel-producing infrastructure a positive step toward a settlement of the Ukrainian conflict.

“Any countries can contribute to a settlement in Ukraine by influencing Kiev and pushing it toward flexibility,” Peskov said, leaving things somewhat vague. He said that disabling of Saudi Arabia’s East-West oil pipeline, which has reportedly knocked more than 4% of global supplies off the market, is cause of serious concern.

“The deterioration of the situation in oil markets cannot but cause concern among global economies,” he emphasized. On that front, the Associated Press newly reports Monday:

A crucial Saudi oil pipeline hit in strikes will be mostly out of service for several weeks for repairs, reports AP citing officials

Specifically concerning the status of the ‘special military operation’ in Ukraine, the Putin spokesman described, “It is becoming increasingly clear to professionals, based on the dynamics at the front lines, that Russia is consistently moving toward achieving its goals in the special military operation.”

He vowed: “The dynamics of advances at the front lines of the special military operation will continue; no one should have any doubts about that.”

And he explained of the weekend New Delhi-hosted major BRICS summit, “Putin reacted positively to the readiness of the leaders of China and India to contribute to the Ukrainian settlement.”

As for Ukraine, President Zelensky over the weekend pointed out that the country’s own energy infrastructure has also subject of frequent attack by Russia.

“The Russians are burning warehouses with food and gas stations, pharmaceutical facilities and ordinary passenger trains, residential buildings and civilian businesses,” Zelensky stated in a Sept.12 X post.

Tyler Durden
Mon, 09/14/2026 – 11:19

via ZeroHedge News https://ift.tt/tOG01Wd Tyler Durden

Beijing Rejects Pause, Slams Dario’s ‘Fearmongering, Cold War Playbook’

Beijing Rejects Pause, Slams Dario’s ‘Fearmongering, Cold War Playbook’

China’s Foreign Ministry and state press had rejected the China provisions of Dario Amodei’s essay calling for a ‘pause’ in AI development, while state security minister and President Xi Jinping laid out what Beijing wants instead.

On Saturday morning, Anthropic CEO Dario Amodei published We Must Pace the Frontier, an essay arguing that the industry must slow the rate at which it improves frontier models and asking Washington to help it do so. By Monday afternoon in Beijing, China’s Foreign Ministry responded. 

The essay’s three steps, are third-party evaluators with permanent, employee-level access inside the labs, which Anthropic committed to unilaterally; coordination among labs in democratic countries on safety standards and the pace of progress, which Amodei concedes needs a narrow antitrust waiver from the U.S. government; and, eventually, agreements with various governments, including China. It also asks Washington to keep the ban on advanced chips and chipmaking equipment, enforce it against smuggling and remote access to overseas data centers, crack down on distillation, prevent model-weight theft, and use the resulting three-to-five-year window to widen America’s lead before any bargain is struck. Sam Altman said OpenAI would match the evaluator commitment. Elon Musk’s reaction was three words: “Dario is right.”

Amodei himself acknowledged the problem. On CBS on Sunday he called the possibility that China and other adversaries would not slow down the “toughest dilemma” in his proposal.

According to Xinhua, Beijing’s Foreign Ministry spokesman Guo Jiakun said on Monday that the development of AI bears on the well-being of all humanity and that all parties should jointly promote its open and inclusive development for good and for all. He added: “Fearmongering, confrontation and vicious competition will only disrupt the process of global AI governance which serves no one’s interest.”

On Sunday evening Beijing time, a Global Times editorial admitted that sure – on the surface the essay appears to be a “rational statement” about global AI security. A closer reading, the paper said, showed it “packed with containment provisions targeting China” and, in essence, a “Cold War playbook” for the AI sector – and that excluding China from the global innovation system would increase, rather than reduce, the “trial-and-error costs and risks of loss of control” in global AI development. China’s AI capabilities “have long ceased to be a variable that can be excluded,” reads the editorial. 

Other Chinese notables chimed in as well. Xiang Ligang, a telecom and technology policy commentator, called Amodei’s rhetoric inappropriate, groundless and hostile. After all, the ‘pacing’ would ultimately require China’s cooperation while advocating restrictions on chips, computing power and models to slow China down. Xiao Qian, vice dean of Tsinghua’s Institute for AI International Governance, attributed the China provisions to commercial pressure: Anthropic’s closed-model approach is competing with Chinese open-source models on cost, performance and the developer ecosystem, and restrictions would protect its position. Liu Shaoshan of the Shenzhen Institute of Artificial Intelligence and Robotics for Society, who the paper says previously worked with Amodei, added that framing AI as decisive for national security turns an AI company into “strategic infrastructure,” which raises barriers to entry and valuations at the same time.

On Wednesday, Beijing’s commerce ministry rejected a joint FBI, NSA and CISA advisory that accused Chinese developers of “aggressive, malicious” efforts to distill capabilities from Claude and GPT, calling the accusation “groundless in fact and without basis in law,” distillation a normal technical and commercial practice, and the advisory further proof that Washington is “seeking to monopolize computing power.”

Amodei’s essay, published three days later, asks the U.S. government to crack down on the same practice in the same document that asks the industry to slow down for the sake of humanity. 

Trump Responds

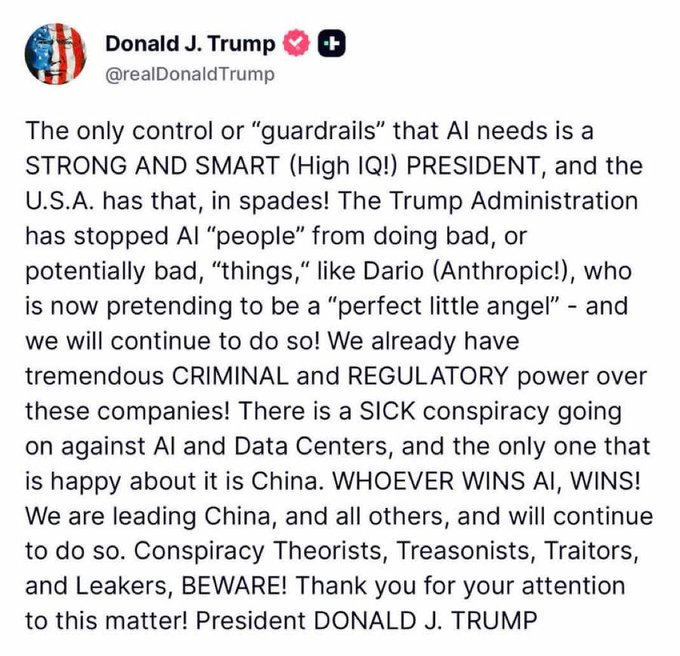
Asked on Thursday in Dallas whether he had any concern about existential risk from AI, Trump said, “No, I don’t have any.” On Sunday, speaking to reporters at his Doonbeg resort during the Irish Open, he said the United States is “leading China in AI” and intends to stay there because “whoever wins AI, wins.” Guardrails were possible, he said; the dire warnings came from “negative forces” raising things he insists will not happen. And on Monday, Trump slammedperfect little angel” Dario over his screed.

House Speaker Mike Johnson made the same argument in institutional form: an emergency session to regulate AI would cost the United States the race with China.

The American Split

The domestic disagreement was already on the record. Barack Obama, at a Manhattan fundraiser on Thursday whose transcript his office released to the New York Times on Sunday, told House Minority Leader Hakeem Jeffries to make AI a governing issue if Democrats take the House. The technology, he said, is “moving very fast in private hands,” and he positioned himself as neither an accelerationist nor a doomer.

David Sacks, the former White House AI czar, told Amodei and Altman in a Saturday-night post to go ahead and slow down if their unreleased models warrant it, but without the antitrust waiver, the regulatory approval process or METR, which he called intertwined with Anthropic’s investors and staff. Demanding a preferred framework as the price of restraint, he wrote, “will look like blackmail of the public and the political system.” China, he added, was “very unlikely to join a global agreement, as you know.” Beijing confirmed the point two days later.

Beijing’s Own Concerns

The most revealing document out of China this weekend wasn’t the response to Dario. State Security Minister Chen Yixin’s article, published Sunday in China Cyberspace, the Cyberspace Administration’s journal, lists six categories of AI risk and, per Bloomberg, makes no mention of the Anthropic and OpenAI calls to slow down.

The first risk is regime security: “hostile forces” using deepfakes and bot networks to wage “cognitive warfare.” The second is cyber offense, and here Chen named Anthropic’s Claude Mythos and OpenAI’s GPT-5.5-Cyber as systems that sharply raise the efficiency of vulnerability discovery and malware development and threaten China’s critical information infrastructure.

Chen describes AI as “a new arena for strategic rivalry among major powers,” warns that countries with an AI advantage may invoke national security to impose technology controls and build closed ecosystems, and calls for powers to “resolutely resist hegemonism, technological barriers, and exclusive blocs.” None of this means Beijing dismisses loss-of-control risk: its cyberspace regulator has carried an explicit loss-of-control scenario in its safety framework since 2024, and Xi said at the World AI Conference in July that AI should “always remain under human control.”

Chen’s focus is on who controls the systems, who can weaponize them, and who is denied the hardware to build them, not about whether the frontier should move more slowly.

Then There’s Xi

Xi’s own contribution came at the BRICS summit in New Delhi on Sunday. China will take the lead in establishing a BRICS AI Open Source Zone to promote cooperation on large language models, AI training and an open AI ecosystem, he said. The logic is to build with the Global South and resist a ruleset written in San Francisco and enforced through American export licenses.

Trump and Xi are due to meet in Washington on September 24, with AI governance expected on the agenda.

Reuters reported that officials were preparing a separate mid-September AI-safety dialogue led by Treasury Secretary Scott Bessent, covering AI-directed cyberattacks, distillation and the prospect of a Chinese model with Mythos-level cyber capabilities; a White House official said “there is currently no planned AI-related meeting in mid-September.” Lizzi Lee of the Asia Society Policy Institute framed Beijing’s question: if Washington wants cooperation on frontier safety while restricting China’s access to frontier compute, “what exactly does that cooperation look like?”

As we laid out Saturday: Chinese open-weight models from DeepSeek, Alibaba’s Qwen, Moonshot’s Kimi, MiniMax and Zhipu are downloadable, forkable and far cheaper to run, with cumulative downloads the Global Times puts above 10 billion. Export controls and evaluator regimes govern American labs and American hardware. They do not retrieve weights that have already been distributed. Amodei’s essay does not pretend otherwise; it is why the proposal climbs to a negotiation with Beijing, and why he ranks a treaty-style limit on recursive self-improvement as “difficult but just on the edge of being possible.” That third step requires a partner. As of Monday, the partner has said what it thinks of the first two.

Tyler Durden
Mon, 09/14/2026 – 11:15

via ZeroHedge News https://ift.tt/OF2nvlJ Tyler Durden

Another Judge Blocks USPS From Implementing New Mail-In Ballot Rule

Another Judge Blocks USPS From Implementing New Mail-In Ballot Rule

Authored by Aldgra Fredly via The Epoch Times,

A federal judge issued a preliminary injunction on Sept. 13 that blocks the U.S. Postal Service (USPS) from enforcing its requirements to tighten mail-in voting rules.

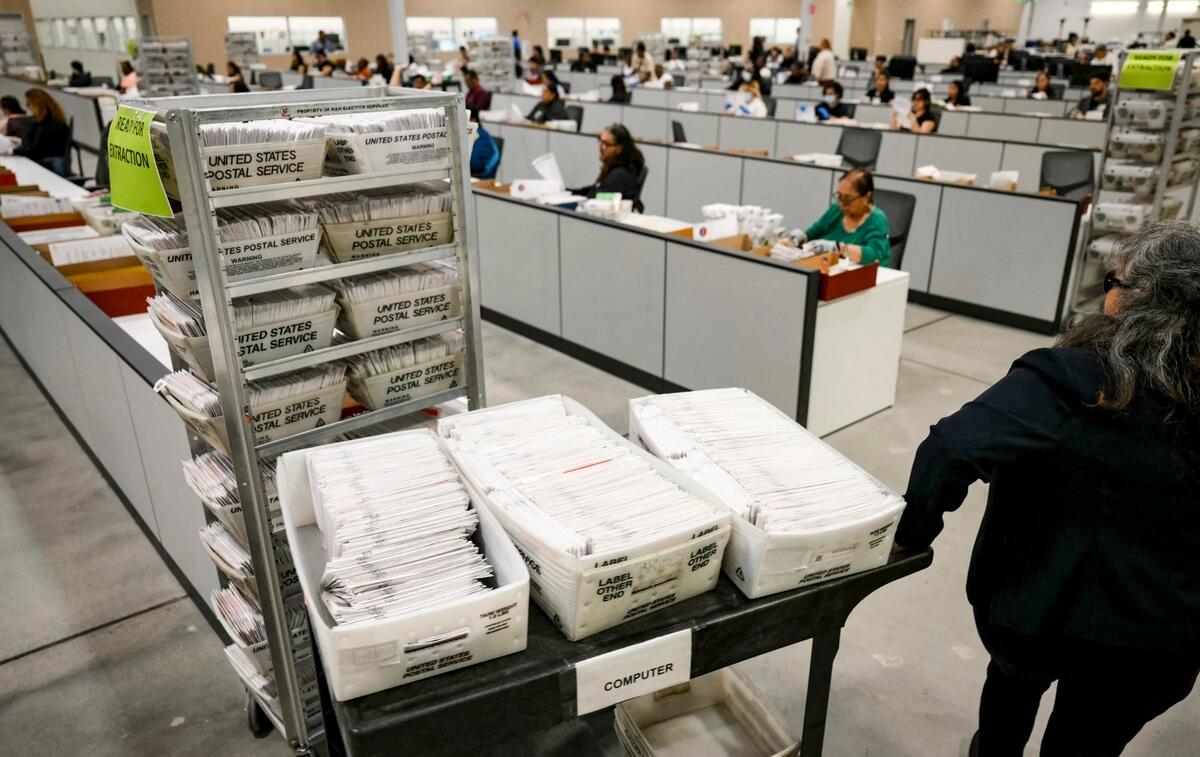
Under the rule, states must supply the agency with lists of mail ballot recipients, and all outbound and return ballot envelopes must bear unique barcodes. It also allows the Postal Service to refuse to deliver ballots that do not comply with the new standards.

In a 24-page ruling, U.S. District Judge Carl Nichols of the U.S. District Court for the District of Columbia said the Postal Service had likely exceeded the authority granted by Congress when issuing the rule. He said that the government had failed to provide any evidence that halting the USPS mail-in voting rule would result in significant fraud in the upcoming elections.

“The key portions of the rule exceed any conception of the outer bounds of these authorities,” Nichols said in the ruling.

“Nothing in the Postal Reorganization Act authorizes the Postal Service to impose new election procedures on state election officials, to create a data collection system for mail-in and absentee voters, or to refuse the transmission of lawful mail because it fails to meet these data collection requirements.”

The Postal Service issued the final rule on Aug. 21 to implement an executive order President Donald Trump signed in March. In the order, Trump wrote that the federal government had a duty to maintain public confidence in election outcomes and that additional measures were needed to enhance election integrity through U.S. mail.

The Trump administration previously said the executive order would help to keep federal elections honest.

The Department of Justice argued on Aug. 31 that the USPS rule is “a regulation of the U.S. mail, and a modest one at that – not a federal takeover of election administration by the Postal Service.”

The judge on Sunday also found that the rule would increase the risk that a significant number of otherwise appropriate absentee or mail-in ballots would not be counted in the upcoming elections.

“The harm of untransmitted ballots – both to voters and candidates – is irreversible, because ‘once the election occurs, there can be no do-over and no redress,'” Nichols said.

The Epoch Times reached out to USPS for comment but did not receive a response by publication time.

A federal appeals court on Sept. 10 declined to pause an injunction issued Sept. 4 by Judge Indira Talwani of the U.S. District Court for the District of Massachusetts, which extended a temporary restraining order issued on Aug. 27 that halted key parts of the Postal Service’s final rule.

The Supreme Court is currently considering the government’s appeal of the order.

Tyler Durden
Mon, 09/14/2026 – 11:00

via ZeroHedge News https://ift.tt/1s0x7hO Tyler Durden

$6 Diesel Flashes 2008 Warning As Energy Shock, AI Slowdown Fears Fuel Perfect Storm

$6 Diesel Flashes 2008 Warning As Energy Shock, AI Slowdown Fears Fuel Perfect Storm

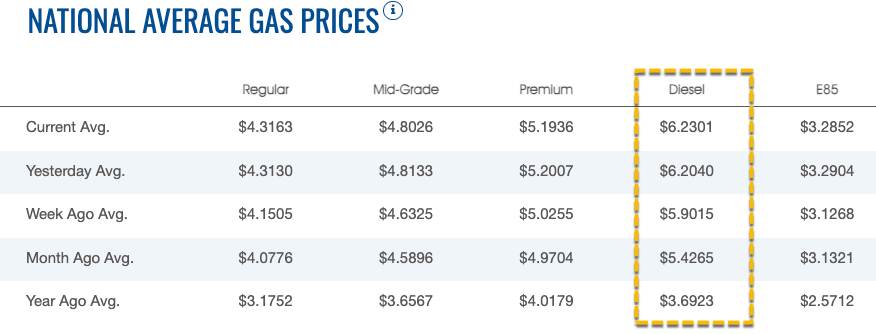
As of Monday morning, AAA’s national average retail diesel price topped $6.23 a gallon as a global refining crisis sparked by the Russia-Ukraine war and compounded by the Gulf conflict sent the price of the most critical fuel powering the industrial world skyrocketing.

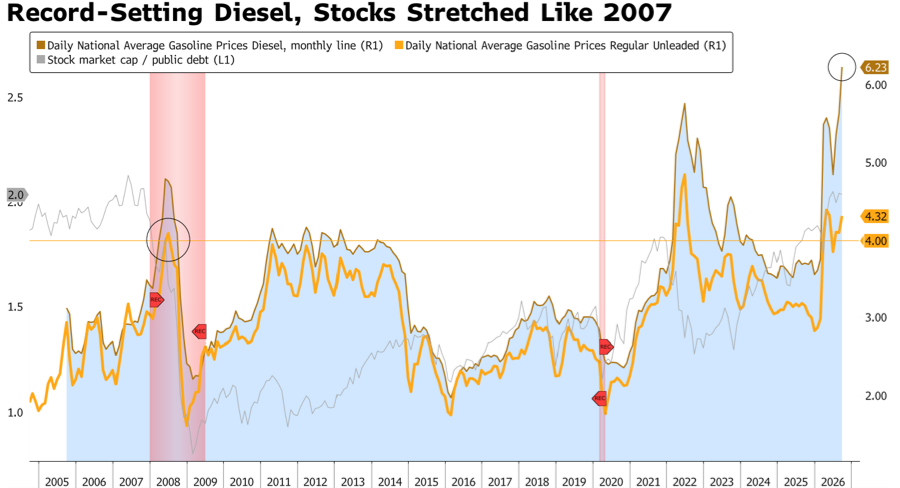
Bloomberg Intelligence senior commodity strategist Mike McGlone warned Monday that “$6 diesel echoes 2008 gasoline shock.”

Commodity spikes tend to sow the seeds of their own reversal, and diesel’s first-ever surge above $6 a gallon may echo gasoline’s 2008 experience. The US daily average gasoline price, at roughly $4.30 on Sept. 11, is only about 4% above its 2008 peak, which helped fuel the Great Recession,” McGlone wrote in a note.

He added, “Elevated stock market valuations could add to the vulnerability.”

On top of a fuel price shock, tech is sliding Monday morning amid fears of an AI slowdown (read the morning note). 

McGlone’s warning comes as Patrick De Haan, head of petroleum analysis at GasBuddy, pointed out at the end of last week that some gas pumps across California hit a record $9.99 per gallon for the industrial fuel.

Any sustained diesel price shock can push inflation higher while slowing economic growth, creating a stagflationary squeeze. Higher energy costs raise production expenses and reduce households’ purchasing power, also denting consumer sentiment. 

The global refining crisis has drawn the White House’s attention. President Trump on Sunday called on Ukrainian President Volodymyr Zelenskyy to halt strikes on Russian diesel infrastructure.

“Zelenskyy has to do one thing. He has to stop knocking out diesel fuel in Russia,” Trump told reporters at the Irish Open yesterday.

“We spoke to Mr. Zelenskyy about it. There are plenty of other targets. Don’t hit diesel fuel, because that’s hurting, that’s hurting the world,” the president said.

Meanwhile, the Trump administration is considering how to use the Defense Production Act to expand US oil refining capacity as the Iran conflict drives up fuel prices.

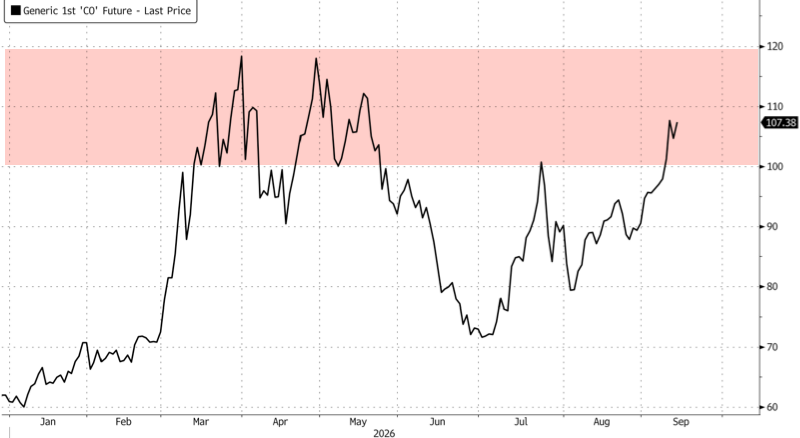
Brent crude traded around $109 a barrel this morning. Last week, the IEA published a report warning of potential demand destruction for industrial fuels. US diesel crack spread remains above $110 a barrel. 

S&P Global Energy warned Thursday that it does not forecast Middle East crude production to return to prewar levels by the end of 2027.

Citi analysts warned Friday that soaring commodity costs and diesel prices will weigh on many of the companies in their coverage universe through the first half of next year:

In 2025, commodity costs were mildly inflationary except for select inputs such as coffee, gas, and tallow which up meaningful +DD%. However, in 2026, commodity inflation has reaccelerated with acute pressure on direct and indirect energy-based products driven by the geopolitical conflict in the Middle East including oil, resins, and diesel/freight costs. Additionally, prices for commodities impacted by tariffs and the global trade dynamics have also increased in 2026 including in aluminum and steel. Many of our companies have highlighted these input cost headwinds, which are pressuring margins this year and which we suspect will remain headwinds into at least 1H’27.

In March, JPMorgan’s head of commodity research, Natasha Kaneva, outlined six policy levers the Trump administration could pull to contain oil prices. Some, including Jones Act waivers and Strategic Petroleum Reserve releases, have already been used. Other options include export restrictions and waiving federal fuel taxes.  

Tyler Durden
Mon, 09/14/2026 – 10:40

via ZeroHedge News https://ift.tt/RPBTkwm Tyler Durden

Trump Says He Might Release More 9/11 Records

Trump Says He Might Release More 9/11 Records

Authored by Zachary Stieber via The Epoch Times,

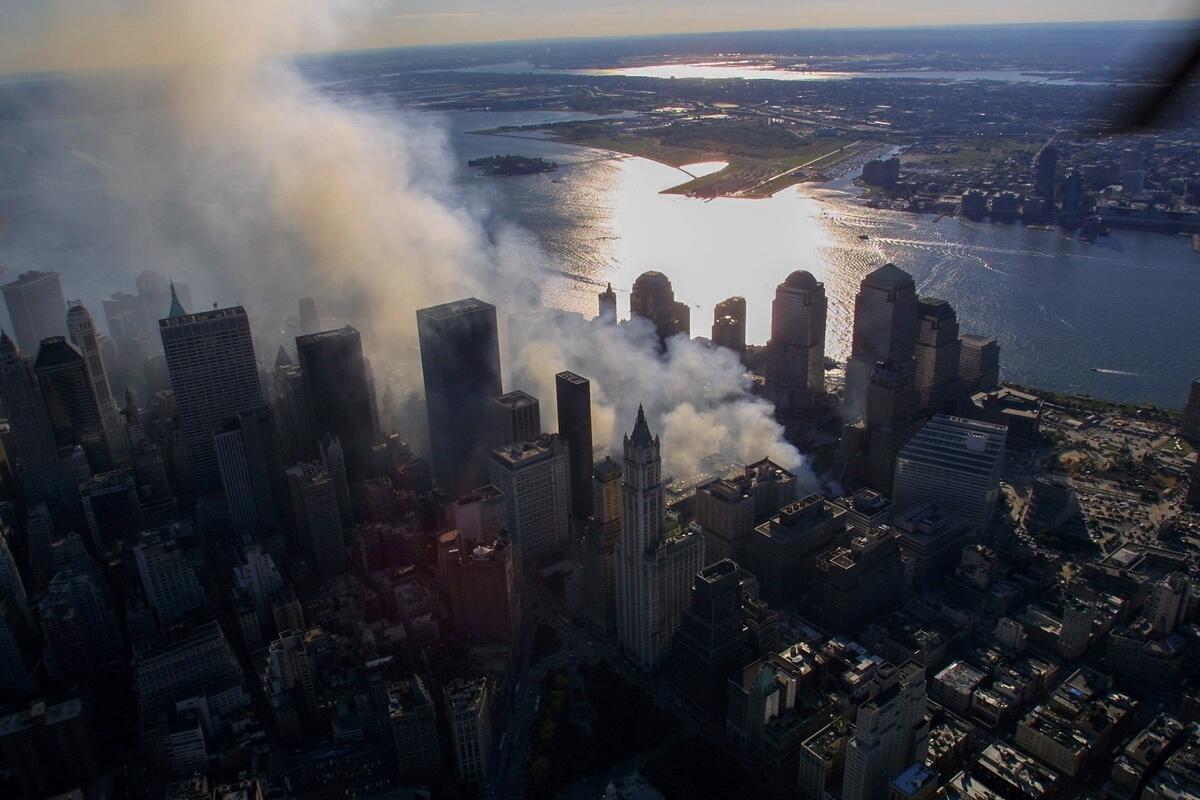
President Donald Trump said on Sept. 13 he might release records related to the Sept. 11, 2001, terror attacks.

“I’m going to look at it when I get back,” he told reporters in Ireland, after being asked about recent requests from families of people who perished in the attacks.

A nephew of Lisa Marie Terry, who was in the North Tower at the World Trade Center when it was struck by one of the planes hijacked by Islamic terrorists, was among those who recently called on Trump to declassify records related to the attacks on the center and the Pentagon.

“For 25 years, the deep state has hidden the truth about what happened that day 25 years ago,” he said during a reading of the names of the victims in New York City on Sept. 11.

“President Trump, you are our last hope. Release the unredacted files that implicate Saudi Arabia while what’s left of the victims’ families are still alive to see it.”

Terry Strada, whose husband, Tom Strada, died in the attacks, said during the same event that past administrations have chosen “to protect the Saudis instead of standing with the 9/11 families” and urged Trump to take action.

Fifteen of the 19 hijackers came from Saudi Arabia, according to the FBI. Some of the families have sued Saudi Arabia, alleging it is liable because officials supported Al Qaeda in the time leading up to the attacks.

A federal judge in 2025 rejected Saudi Arabia’s motion to dismiss the case, concluding there was evidence at that stage that two Saudi Arabian officials assisted the hijackers and that the employees were acting within the scope of their employment.

Lawyers for Saudi Arabia argued that the nation was partnered with the United States against terrorism, Al Qaeda, and its founder, Osama bin Laden, in the 1990s. They disputed allegations that the two Saudi officials knowingly assisted the hijackers as part of a government effort.

President Joe Biden, while in office, ordered the declassification of some records related to 9/11, including a summary of an FBI report from 2016 that listed some Saudi nationals as having connections to 9/11 hijackers.

The Trump administration on Sept. 11 released declassified records showing multiple presidents were warned that Bin Laden was plotting to hijack aircraft and carry out an attack inside the United States, as well as interviews conducted by the 9/11 Commission with top officials, including former President Bill Clinton.

New York City officials also recently made public thousands of documents related to 9/11, including memoranda from city officials discussing their worries about air quality in lower Manhattan in the wake of the attacks.

Tyler Durden
Mon, 09/14/2026 – 10:25

via ZeroHedge News https://ift.tt/Xj9AyLu Tyler Durden

Key Events This Week: Fed, BOJ And BOE; Also Retail Sales, Import Prices And Bessent

Key Events This Week: Fed, BOJ And BOE; Also Retail Sales, Import Prices And Bessent

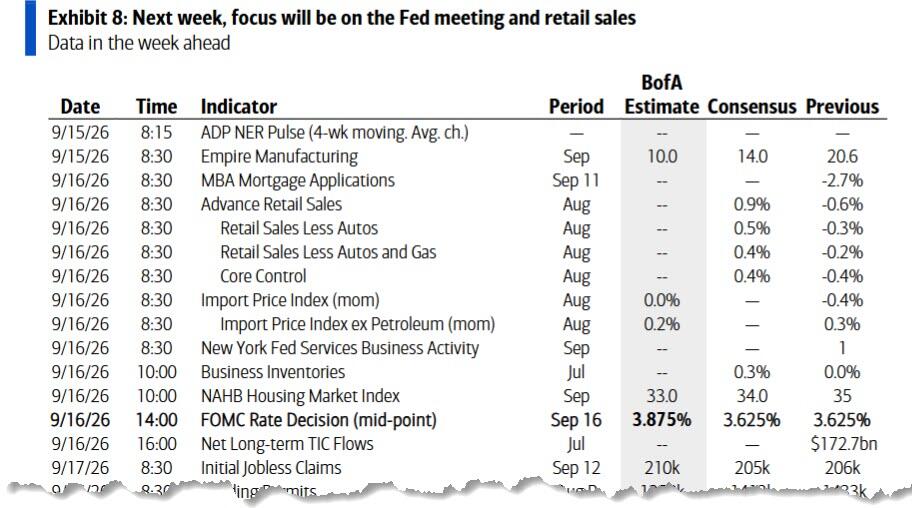
It’s a bumper week for central bank decisions, with the Fed (Wednesday), BoE (Thursday) and BoJ (Friday) all meeting. Central banks aside, key data releases include US retail sales (Wednesday) and industrial production (Friday), UK inflation (Wednesday) and labor market data (Tuesday), economic activity in China (tomorrow), and inflation and trade in Japan (Friday and Wednesday respectively). Other events include the annual testimony of the US Treasury Secretary namely Bessent (tomorrow), and the State of the Union address in Europe (Wednesday).

Delving into more detail now, DB’s Jim Reid writes that the main event for markets will be the Fed’s decision on Wednesday. Deutsche economists have long expected a 25bp rate hike with the market now at 87% this morning up from around 35% two Friday’s ago just before Warsh’s Jackson Hole speech. Such a move would take the target range to 3.75%-4.00%. DB economists believe the accompanying projections are likely to show a somewhat stronger growth outlook alongside still-elevated inflation. They have also added an extra hike in March to their forecast which now makes it 75bps of hikes over the next 7 months. A big focus will be Warsh’s press conference and how he squares the circle between a dislike of forward guidance and calming markets which are baying for more info.  

Friday’s inflation data strengthened the case for action this week. Core CPI rose by 0.29% in August, a touch above expectations and up from 0.22% in July. The details were also firm, with notable strength in wireless services, airfares and lodging-away-from-home prices. Meanwhile, last Thursday’s PPI report contained hawkish elements, including stronger hospital and international airfare prices. Combining the latest CPI and PPI data, DB economists estimate August core PCE increased by 0.27%, a pace they do not view as consistent with sufficient progress back towards the Fed’s inflation target.

Attention will now turn to incoming US activity data. Tomorrow, markets will receive Treasury Secretary Bessent’s annual testimony before the House Financial Services Committee. On Wednesday, August US retail sales are released and economists expect a rebound to +0.8% month-on-month, following July’s -0.6% decline. They also forecast ex-auto sales at +0.5% and retail control sales at +0.4%, arguing that July’s weakness looked more like a temporary pause in consumer spending than the start of a broader slowdown. On Friday, industrial production is due and economists expect growth to edge up to +0.3% from +0.2% previously.

Looking beyond the US, the BoE announces its latest policy decision on Thursday. DB economists expect Bank Rate to remain unchanged at 3.75%, with a 6-3 voting split, and continue to see the MPC remaining relatively cautious compared with some other major central banks. However, the bond market and energy moves at the end of the week make it a closer call than it was, with futures pricing in a 23% probability of a move, up from under 10% early last Thursday. Before that, UK labor market data are released tomorrow, while August CPI is due on Wednesday. Economists expect headline inflation to rise to 3.04% YoY, while core CPI eases slightly to 2.53% YoY. UK retail sales, together with the GfK consumer confidence survey, follow on Friday.

In Asia, the BoJ concludes its meeting on Friday. DB’s economists expect a 25bp rate hike (futures price in a 98% probability now), and argue that external considerations, including pressure for greater FX stability, are likely to be at least as important as domestic economic fundamentals in driving the decision. Japan also releases trade data and core machine orders on Wednesday, followed by national CPI on Friday, where DB economists expect core inflation excluding fresh food to remain at 1.8% YoY.

China’s August activity indicators are released tomorrow. DB economists expect industrial production growth to accelerate to 5.0% YoY from 4.5%, while retail sales and fixed-asset investment should also improve. Elsewhere, Germany’s ZEW survey is due tomorrow, while the ECB publishes its consumer expectations survey on Friday.

On the political front, the European Commission President delivers the annual State of the Union address on Wednesday, setting out priorities for the year ahead. Finally, the NATO’s Military Committee Conference takes place in Copenhagen at the end of the week.

Courtesy of DB, here is a day by day recap of the week’s main events:

Monday September 14

  • Data: Japan July capacity utilisation, Canada August CPI, July manufacturing sales
  • Central banks: ECB’s Lagarde, Schnabel and Cipollone speak

Tuesday September 15

  • Data: US September Empire manufacturing index, China August retail sales, industrial production, home prices, investment, UK July average weekly earnings, unemployment rate, August jobless claims change, Germany August wholesale price index, September Zew survey, Italy July trade balance, general government debt, Eurozone September Zew survey, July trade balance, Canada August existing home sales, July wholesale sales ex petroleum
  • Central banks: ECB’s Cipollone and Reinesch speak
  • Auctions: US 20-yr Bond (reopening, $13bn)
  • Other: Annual testimony of the Secretary of the Treasury on the state of the international financial system before the House Financial Services Committee

Wednesday September 16

  • Data: US September NAHB housing market index, New York Fed services business activity, August retail sales, import price index, export price index, July business inventories, total net TIC flows, UK August CPI, RPI, PPI, July house price index, Japan August trade balance, July core machine orders, Eurozone July industrial production, Canada August housing starts, July building permits
  • Central banks: Fed’s decision, ECB’s Vujcic speaks, BoC’s summary of deliberations
  • Other: European Commission President von der Leyen President delivers the State of the Union address to the European Parliament

Thursday September 17

  • Data: US September Philadelphia Fed business outlook, August housing starts, building permits, pending home sales, initial jobless, Canada August industrial product price index, raw materials price index, July international securities transactions, New Zealand Q2 GDP
  • Central banks: BoE’s decision, ECB’s Lane and Rehn speak
  • Auctions: US 10-yr TIPS (reopening, $19bn)

Friday September 18

  • Data: US August industrial production, capacity utilisation, leading index, UK September GfK consumer confidence, August retail sales, Japan August national CPI, Germany August PPI, Italy July current account balance, Eurozone July ECB current account, construction output
  • Central banks: BoJ’s decision, ECB’s consumer expectations survey
  • Other: NATO’s Military Committee Conference (Sep. 18-19)

Finally, looking at just the US, the key economic data releases this week are the import prices report — because of its potential implications for core PCE — and the retail sales report on Wednesday. The September FOMC meeting is on Wednesday. The post-meeting statement will be released at 2:00 PM ET, followed by Chairman Warsh’s press conference at 2:30 PM.

 Monday, September 14 

  • There are no major economic data releases scheduled. 

Tuesday, September 15 

  • 08:30 AM Empire State manufacturing survey, September (consensus 15.0, last 20.6)

Wednesday, September 16 

  • 08:30 AM Retail sales, August (GS +0.6%, consensus +0.8%, last -0.6%); Retail sales ex-auto, August (GS +0.6%, consensus +0.5%, last -0.3%); Retail sales ex-auto & gas, August (GS +0.5%, consensus +0.4%, last -0.2%); Core retail sales, August (GS +0.6%, consensus +0.4%, last -0.4%): We estimate nominal core retail sales increased 0.6% in August (ex-autos, gasoline, and building materials; month-over-month SA). Our forecast in part reflects a 0.4pp boost from a rebound in the nonstore retailers category, which was depressed in July by an earlier-than-usual Amazon Prime Day. (Amazon Prime Day is normally conducted in July—and the seasonal factors expect high July sales as a result—but was held in June this year). We estimate nominal headline retail sales increased 0.6%, reflecting higher gasoline prices and auto sales but limited growth in food services and building materials sales.
  • 08:30 AM Import price index, August (consensus +0.5%, last -0.4%): The import prices report contains the remaining source data relevant to estimating August core PCE: the import price index for air passenger fares. Based on the details of last week’s CPI and PPI reports, we currently estimate that the core PCE price index rose 0.26% in August, corresponding to a year-over-year rate of +3.16% after accounting for our forecast of the revisions that will result from the methodological changes that will be implemented with the August PCE report.
  • 10:00 AM Business inventories, July (consensus +0.8%, last flat)
  • 10:00 AM NAHB housing market index, September (consensus 34, last 35)
  • 02:00 PM FOMC statement, September 15-16 meeting: As discussed in our FOMC preview, the FOMC is likely to raise the funds rate to 3.75-4.00%. Although the August CPI report had little impact on our inflation view, it pushed market pricing of a hike to nearly 90%, high enough that the FOMC will likely want to avoid the market reaction that would likely follow from remaining on hold. We continue to expect two cuts in 2027 but now expect them in September and December (vs. June and December previously) and have raised our forecast for the terminal rate to 3.25-3.5% (vs. 3-3.25% previously). We suspect that the FOMC will want to nudge the market away from pricing an October hike too confidently but will not do it in the statement. Instead, Chairman Warsh would likely hint in his press conference at waiting a bit longer to collect more information before deciding on further steps. The key question for the meeting is whether the median dot will show one hike or two in 2026. We expect a 10-8 majority to show one hike because some participants might be ambivalent about the first hike and some might want to avoid pushing market expectations any higher. 

Thursday, September 17 

  • 08:30 AM Philadelphia Fed manufacturing index, September (GS 30.0, consensus 32.1, last 47.4)
  • 08:30 AM Initial jobless claims, week ended September 12 (GS 195k, consensus 208k, last 206k); Continuing jobless claims, week ended September 5 (consensus 1,780k, last 1,774k): We estimate that initial claims declined by 11k to 195k in the week ended September 12, reflecting difficulties seasonally adjusting around the Labor Day holiday, which occurred relatively late this year.
  • 08:30 AM Housing starts, August (GS +8.9%, consensus +6.9%, last -12.4%); Building permits, August (consensus -1.5%, last +4.3%):  We forecast that housing starts increased by 8.9%, primarily reflecting significant increases in building permits last month. 
  • 10:00 AM Pending home sales, August (GS -2.0%, consensus flat, last -2.3%)

Friday, September 18 

  • 09:15 AM Industrial production, August (GS +0.4%, consensus +0.3%, last +0.2%); Manufacturing production, August (GS +0.4%, consensus +0.3%, last +0.2%); Capacity utilization, August (GS 76.4%, consensus 76.4%, last 76.3%): We estimate industrial production increased by 0.4% in August, largely reflecting strong auto and electricity production. We estimate capacity utilization edged up to 76.4%.
  • 09:30 AM Fed Vice Chair for Supervision Michelle W. Bowman speaks: Fed Vice Chair for Supervision Michelle W. Bowman will deliver a speech on stress testing in London. Speech text and Q&A are expected.
  • 11:45 AM Kansas City Fed President Schmid (FOMC non-voter) speaks: Kansas City Fed President Jeff Schmid will speak on payments and banking at the Independent Community Bankers of Colorado Annual Convention. Speech text and Q&A are expected. On August 4, Schmid said that “inflation has been too high across a broad-based and growing cross-section of goods and services.” He further explained on August 27 that he believes interest rates “might be accommodative on the short end” and that he likely would have dissented at the July FOMC meeting.

Source: DB, Goldman, BOfA

Tyler Durden
Mon, 09/14/2026 – 10:15

via ZeroHedge News https://ift.tt/pjP3DtU Tyler Durden

We Can’t Afford $5,000 “Dividend” Checks

We Can’t Afford $5,000 “Dividend” Checks

Submitted by QTR’s Fringe Finance

While the stock market implodes on or ahead of schedule, as predicted, I had another revelation last night that anyone with a first-grade understanding of math could have also arrived yet. We can’t afford this $5,000 dividend check idea.

I mean, we can’t really afford anything as a country right now, but it is arguably the worst moment in history to randomly hand out $5,000 to citizens for no reason.

I would love $5,000. You would love $5,000. I have yet to encounter the American who opens his mailbox, finds a check for five grand from the United States Treasury and screams, “Goddammit, not this again.”

But unfortunately, there is a very small problem with President Trump’s latest proposal to send every adult American a $5,000 “Trump dividend” if Republicans retain control of Congress in November: we don’t have the f*cking money.

Trump unveiled the idea at the Republican convention in Dallas, promising a $5,000 payment to every adult U.S. citizen if Republicans win the House and Senate. With roughly 240 million adult citizens, Reuters estimates the program would cost approximately $1.2 trillion. Trump’s explanation for how we can afford this is essentially that America is now swimming in money. “We’re taking in trillions, trillions of dollars,” he said while discussing the proposal.

And while tariff revenue has increased substantially, it isn’t remotely close to producing the trillions of dollars necessary to fund something like this. The federal government is already spending considerably more than it collects.

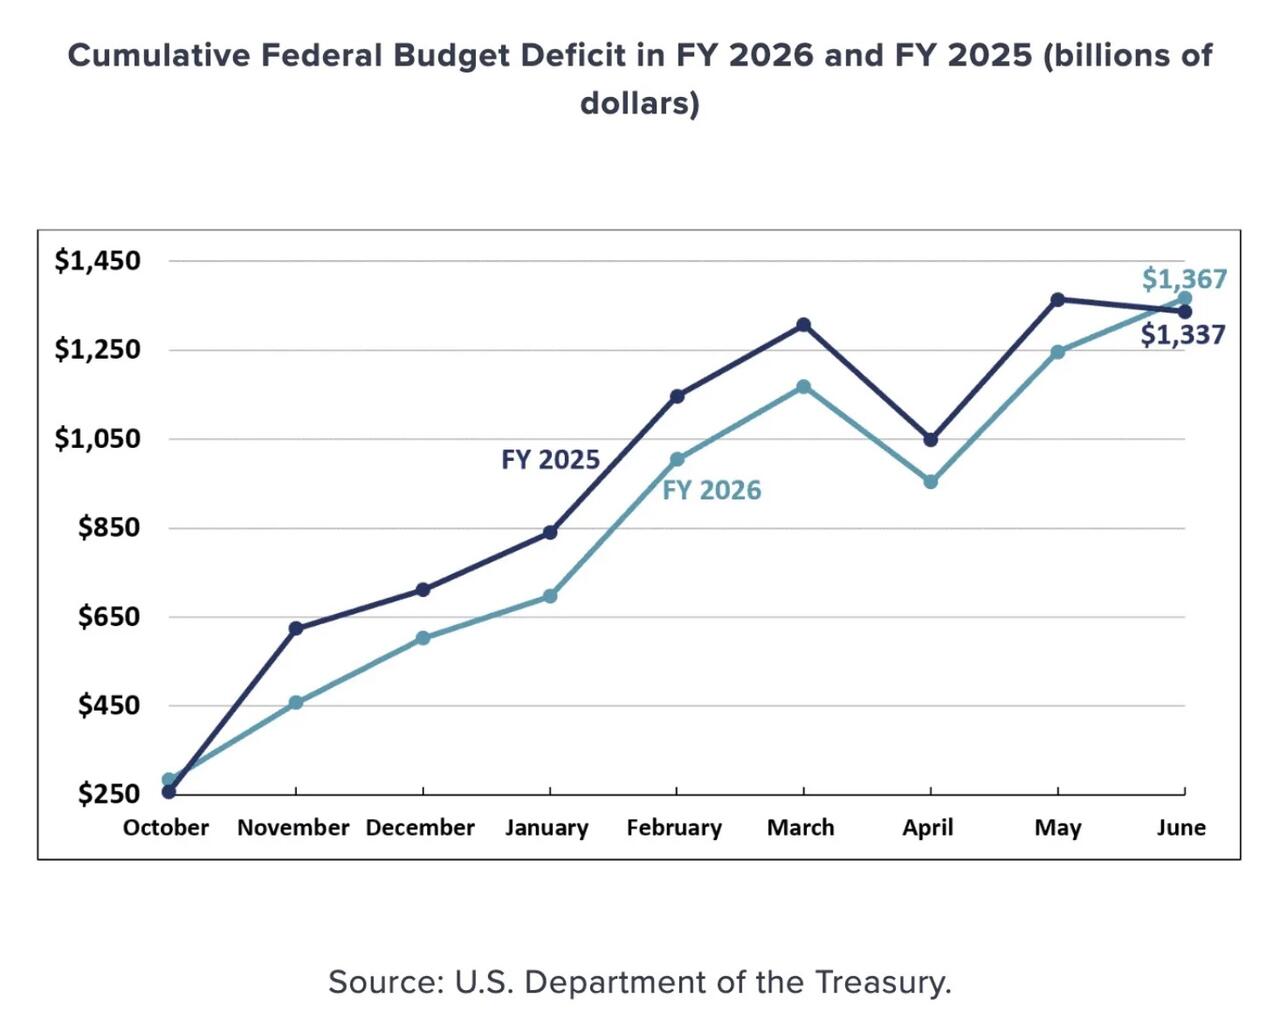
According to the Congressional Budget Office, the federal deficit reached roughly $1.8 trillion during the first ten months of fiscal 2026, about $169 billion more than during the same period last year. CBO estimates the full-year deficit will be roughly $2.1 trillion.

Think about what that means. We aren’t discussing what to do with a surplus. There isn’t some giant extra pile of money sitting in Washington. We’re already borrowing roughly $2 trillion a year to cover what the government spends, and now we’re contemplating borrowing another $1.2 trillion so Washington can mail everybody a check.

We’re calling it a “dividend” but that’s not generally how dividends work. If a company loses $2 trillion a year, borrows another $1.2 trillion and then distributes the borrowed money to shareholders, CNBC does not call it an exciting new capital return program. Eventually somebody from the SEC starts asking questions.

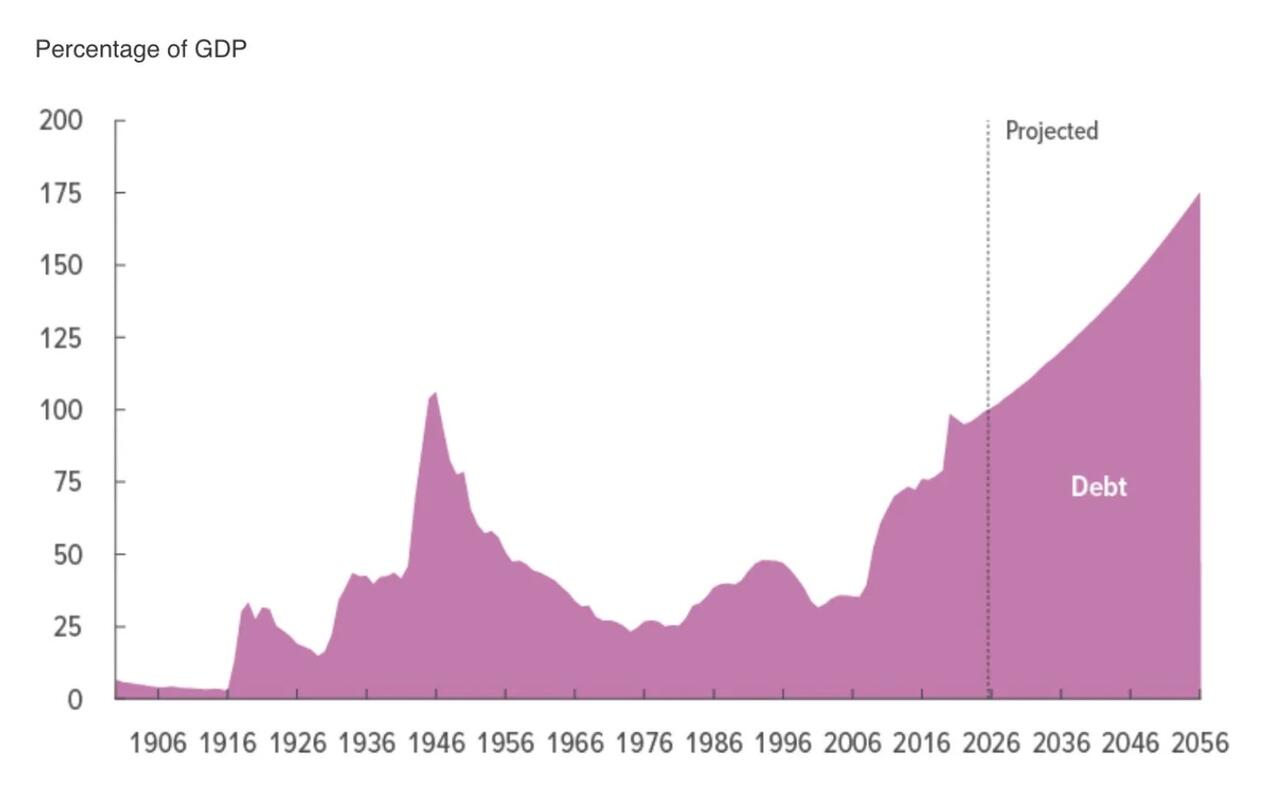
Meanwhile, the gross national debt has now blown through $40 trillion. Debt held by the public is roughly $32 trillion and, according to the Congressional Budget Office’s latest budget outlook, will equal about 101% of GDP this year. CBO projects that it will surpass the post World War II record of 106% of GDP around the end of this decade and reach approximately 120% by 2036.

This seems like a peculiar moment to find a new direction to spray cash we don’t have. And as if the existing fiscal situation weren’t sufficiently hilarious, America has simultaneously found itself with another extremely expensive item on its shopping list: weapons. Lots and lots of weapons.

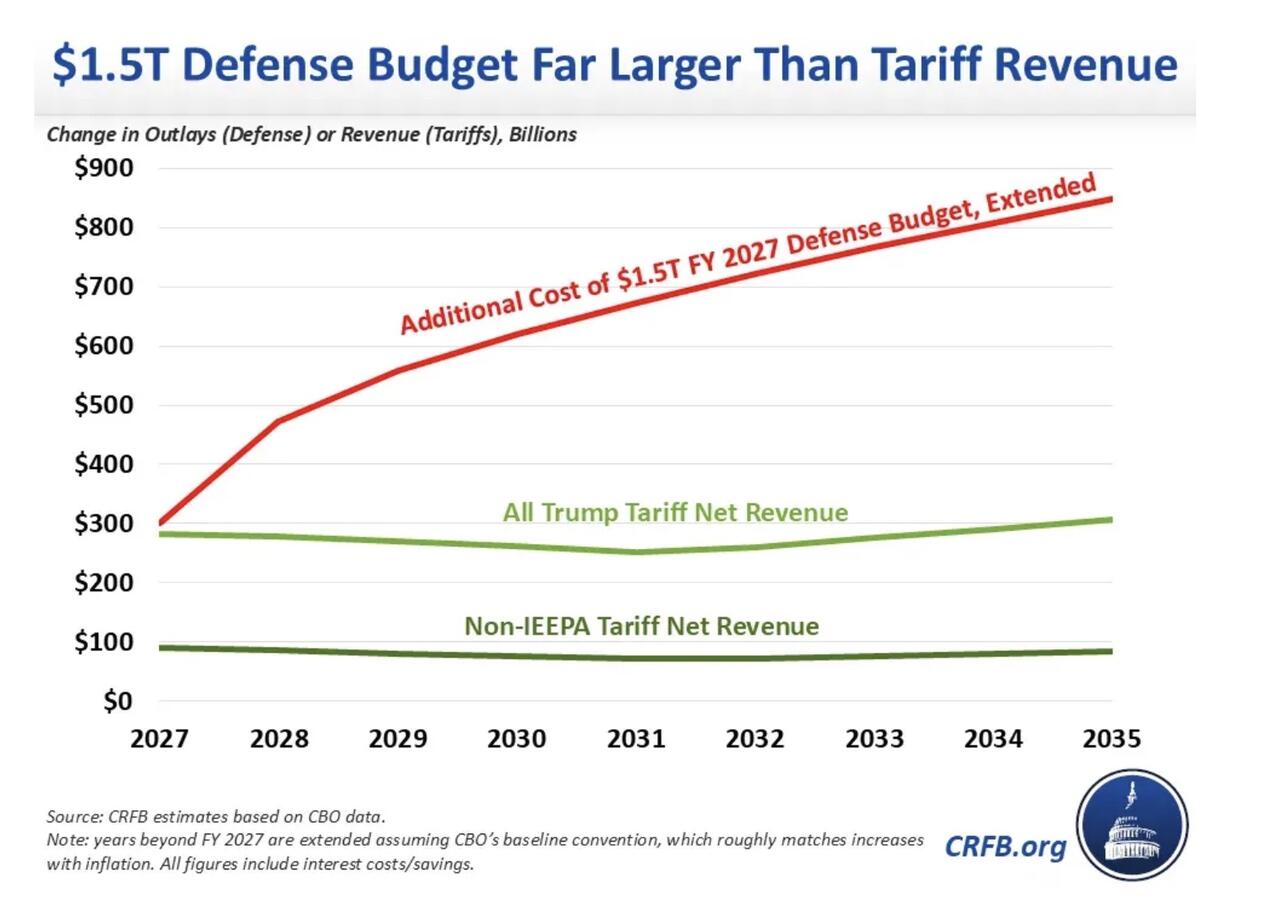
The Pentagon has proposed a $1.5 trillion defense budget for fiscal 2027, versus roughly $900 billion approved for 2026, the largest year-over-year increase in defense spending in the postwar era and a budget I think could massively benefit one sector of the stock market. The administration says the increase includes major spending on missiles, drones, ships, aircraft, missile defense and rebuilding the defense industrial base. Iran-related costs would require additional funding.

And as we’re finding out now, the war with Iran has burned through significant quantities of expensive American munitions, and defense contractors are already anticipating years of replenishment orders. Reuters reported in July that conflicts including Iran and Ukraine have depleted Pentagon inventories that will have to be rebuilt.

So let me get this straight: our current financial plan appears to be to run a roughly $2 trillion deficit, fight an expensive war, replace a gigantic pile of missiles, dramatically increase defense spending and then mail everybody $5,000.

I am beginning to understand why the bond market has questions.

There is also the Strategic Petroleum Reserve, which has been drawn down enormously from its historical peak and remains far below the levels of only a few years ago. That’s particularly relevant when America is simultaneously dealing with a Middle Eastern war that has helped send oil back above $100 per barrel.

Emergency reserves exist to provide flexibility when bad things happen, but using them means eventually replenishing them. That costs money too.


🔥 85% OFF FOREVER IF YOU SUBSCRIBE TODAY: I am again offering an 85% discount to anyone that wants to become a Fringe Finance annual subscriber today. It’s a discount you can keep and stays applied for as long as you wish to remain a subscriber: Get 85% off forever


The Treasury market isn’t exactly celebrating the fiscal situation either. The benchmark 10-year Treasury yield has recently approached 5% and higher yields are especially nasty when you’re carrying tens of trillions of dollars in debt because old securities eventually mature and have to be refinanced at higher rates.

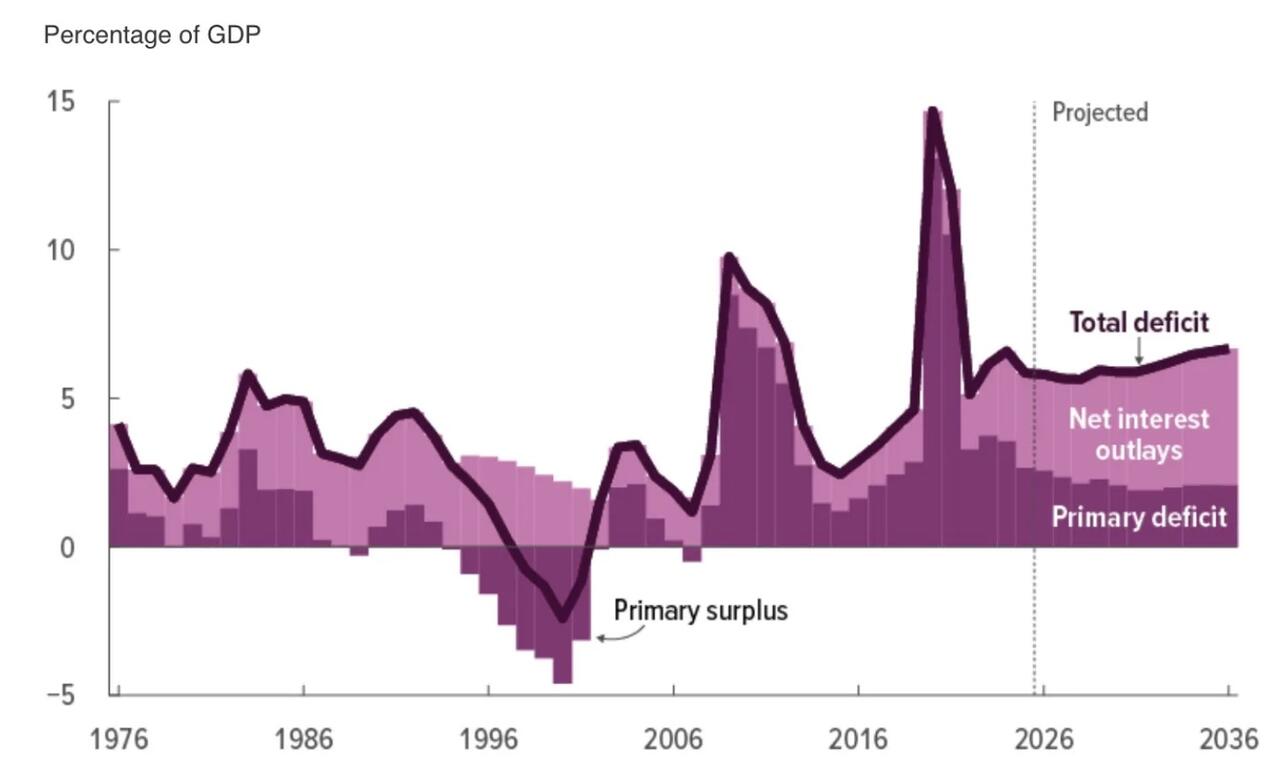
And interest expense is already becoming one of the biggest problems in the federal budget. The CBO projects that persistent primary deficits and rising interest costs will push the annual federal deficit from roughly $2 trillion today toward $3.1 trillion by 2036. So the ultimate cost of another $1.2 trillion giveaway isn’t necessarily $1.2 trillion. If we borrow the money, it’s $1.2 trillion plus the interest required to carry that debt indefinitely.

Trump has explicitly tied the $5,000 payments to Republicans retaining control of Congress in the November midterms. Whatever one thinks of the policy itself, attaching a four-figure government payment directly to an election outcome inevitably makes the proposal look at least partly like campaign politics, though it isn’t much different than Zohran Mamdani promising free everything for New York City to get elected.

The depressing answer to all of this is the one nobody wants to hear. America probably needs fewer promises of free money, not more of them. There is nothing particularly exciting about cutting spending, narrowing deficits, paying down debt and restoring some semblance of discipline to the federal balance sheet. Nobody wins a standing ovation by walking onto a stage and announcing, “Good news everybody, you’re getting nothing, but let me explain why that makes sense given the last half century of gross overconsumption and money printing.”

Eventually somebody has to pay the bill. We have more than $40 trillion in gross federal debt, annual deficits running around $2 trillion, debt held by the public roughly equal to the entire annual output of the American economy, rapidly rising interest costs, enormous new defense requirements and a bond market increasingly demanding more compensation to finance all of it.

The CBO’s long-term projections make the basic problem difficult to avoid: under current policy, debt keeps rising faster than the economy and deficits continue widening. Eventually stabilizing that trajectory requires some combination of lower spending and higher revenues, and waiting makes the necessary adjustment larger.

I certainly prefer the version of reality where somebody gives me $5,000, trust me. A $5,000 check would feel fantastic when it arrived. But dividends generally come from profits, and Uncle Sam isn’t turning a profit. He’s trying to put his bar tab on a fifth credit card that has been declined and has turned to looking for change under the barstools to pony up for one last beer. And the bartender is starting to look nervous.

Now read:

QTR’s Disclaimer: Please read my full legal disclaimer on my About page hereThis post represents my opinions only. In addition, please understand I am an idiot and very often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning, meaning if I’m long I could sell or if I’m short I could cover at any time.

Contributor posts, guest posts and curated posts have been hand selected by me, but have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author or reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.

I cannot guarantee the accuracy of any or all facts and figures included in this article though I made an effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional, which I am not.

This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things I’m bearish on. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.

Starting in 2026, I have been attempting to no longer actively trade as much as I once did (read my story here). My goal is for my investing/saving to be done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. It is possible I could own, have exposure to, or not own anything, at any point. In an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.

Any of my positions can change immediately as soon as I publish, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier. Hence, why I am a writer.

The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. Many times I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour.

Also, again I just straight up get shit wrong a lot. I mention it multiple times because it’s that important you understand.


Tyler Durden
Mon, 09/14/2026 – 09:45

via ZeroHedge News https://ift.tt/YRbMyqi Tyler Durden

Fed Rate Hikes Will Increase US Interest Costs By $50 Billion

Fed Rate Hikes Will Increase US Interest Costs By $50 Billion

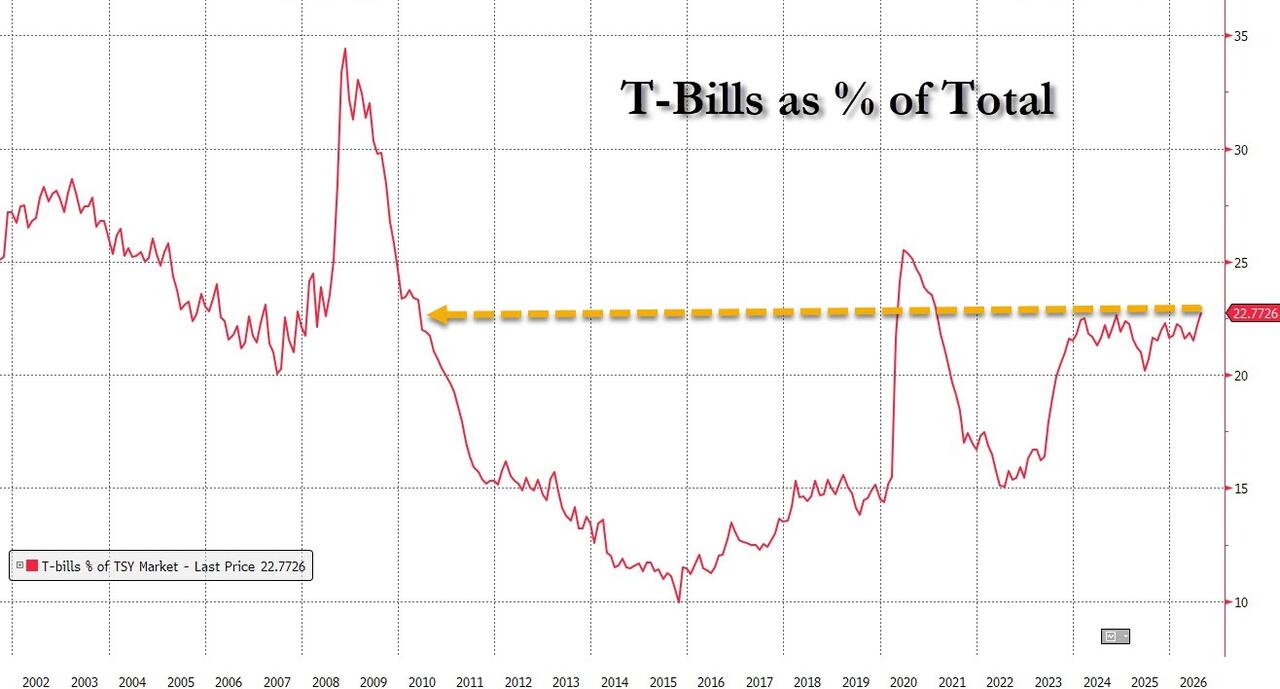
The biggest problem with the “short-terming” of the US Treasury stock, which under Bessent’s extension of Yellen’s Activist Treasury Issuance playbook, which pushed the percentage of T-Bills as a percentage of total debt to 23% – the highest since 2010 excluding the emergency surge during the covid crisis which relied entirely on Bills for government funding and briefly pushed the Bill percentage above 25% – even as total US debt rose above $40 trillion for the first time ever… 

… is that any rate hike will immediately increase the amount the country is spending on interest.

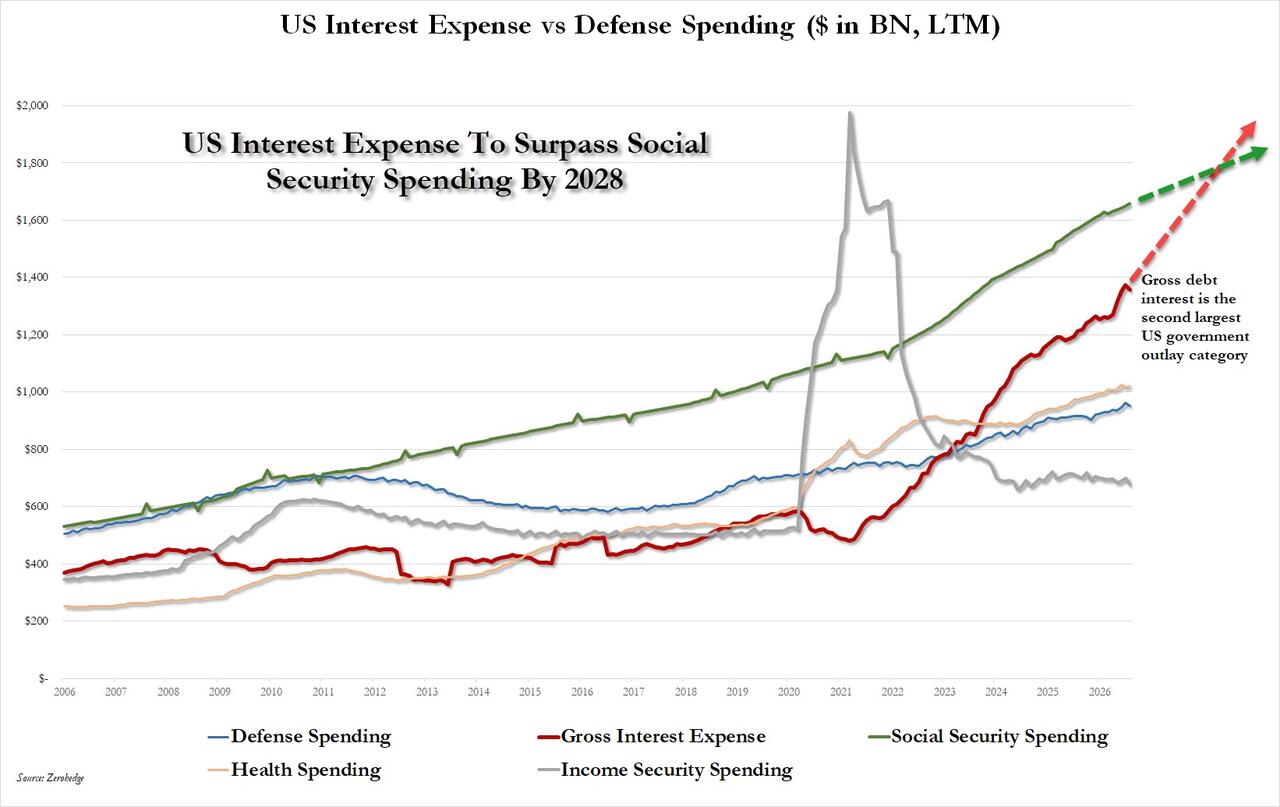
Which is especially concerning because, as we wrote on Friday when discussing the August budget deficit, gross US interest (for the LTM period) is now a record $1.4 trillion and is set to surpass Social Security as the largest US outlay within 2 years, likely hitting $2 trillion before 2030.  

The dramatic deterioration in the US fiscal picture prompted BofA’s chief economist Aditya Bhave to pen a report (“In the interest of time“, available to pro subs) in which he wrote that “the recent rise in interest rates, particularly at the long-end, coupled with US total debt crossing the $40tn threshold sparked a wave of commentary on the US fiscal picture.”

According to Bhave, while elevated deficits since the pandemic have certainly contributed to the higher term premium, it’s unlikely that crossing the $40tn threshold contributed to the recent increase in long-term yields. That’s because markets tend to respond to changes in the expected path of deficits and Treasury issuance rather than the level of debt alone. Importantly, there has been no policy announcement or fiscal development that meaningfully altered those expectations recently.

Instead, BofA notes, it appears that the recent rise in yields has been driven by higher inflation expectations owing to the rise in energy prices and questions over the Fed’s commitment to its price stability mandate, which were partially quieted by Warsh at Jackson Hole.

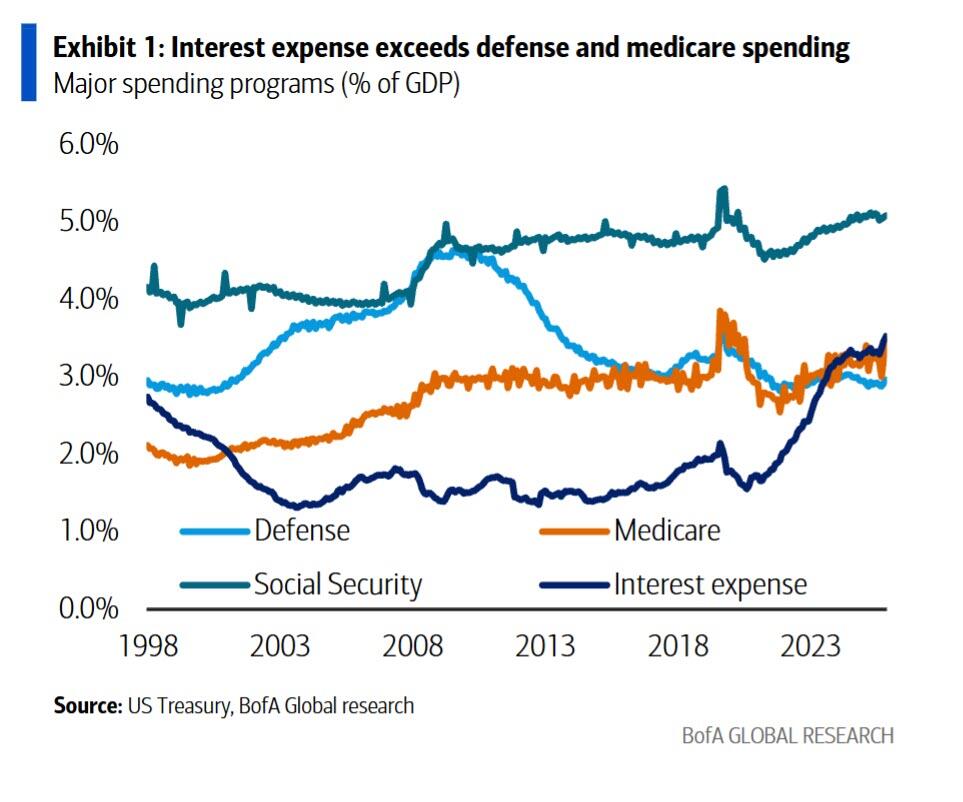
Regardless of what has driven the rise in yields, the BofA economist team cautions that higher interest rates across the curve do warrant a renewed focus on deficits. The deficit this year is on pace to once again eclipse 6% of GDP and a major reason for that is rising interest expense which has exceed spending on Defense and Medicare. The trend in interest costs is also notably worse than Medicare, Defense Spending and even Social Security, which have been more stable.

Source: BofA

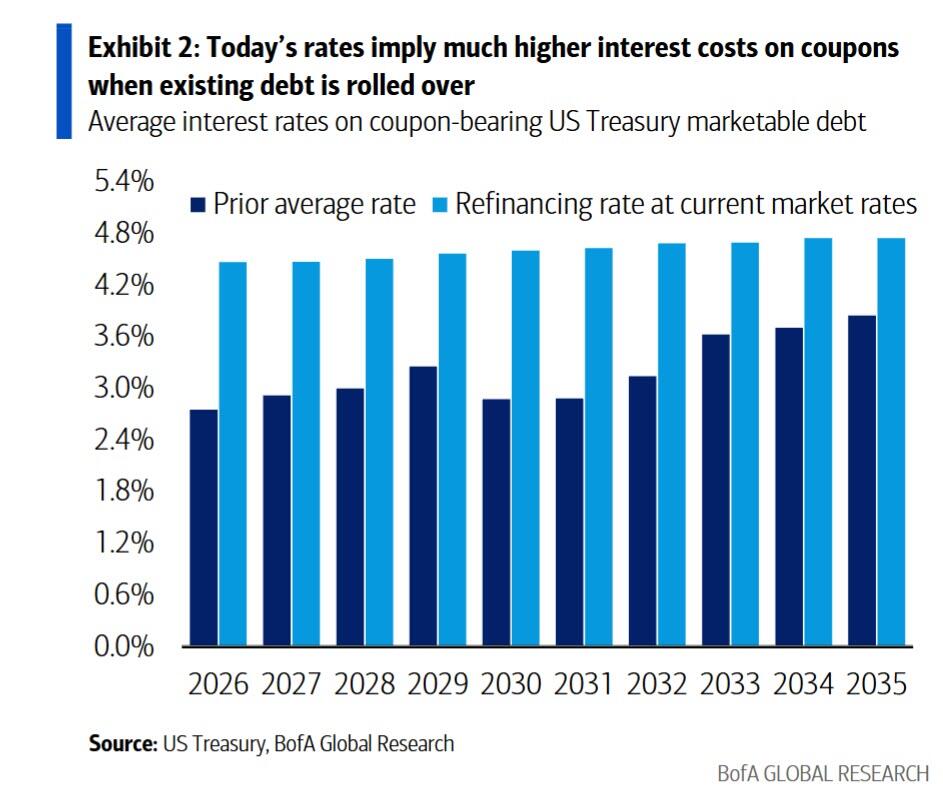
And while the trend of US interest expense growth is already ruinous, here BofA repeats what we said above, namely that the current level of interest rates is likely to exacerbate these trends as Treasury refinances maturing debt at higher borrowing costs.

According to BofA calcs, the average interest rate on outstanding marketable Treasury debt remains well below prevailing market yields, at roughly 3.4%. Looking specifically at coupon-bearing securities, current market rates imply that debt rolled over in coming years will be refinanced at interest rates approximately 1.4 percentage points higher, on average, than those on the securities being retired.

Source: BofA

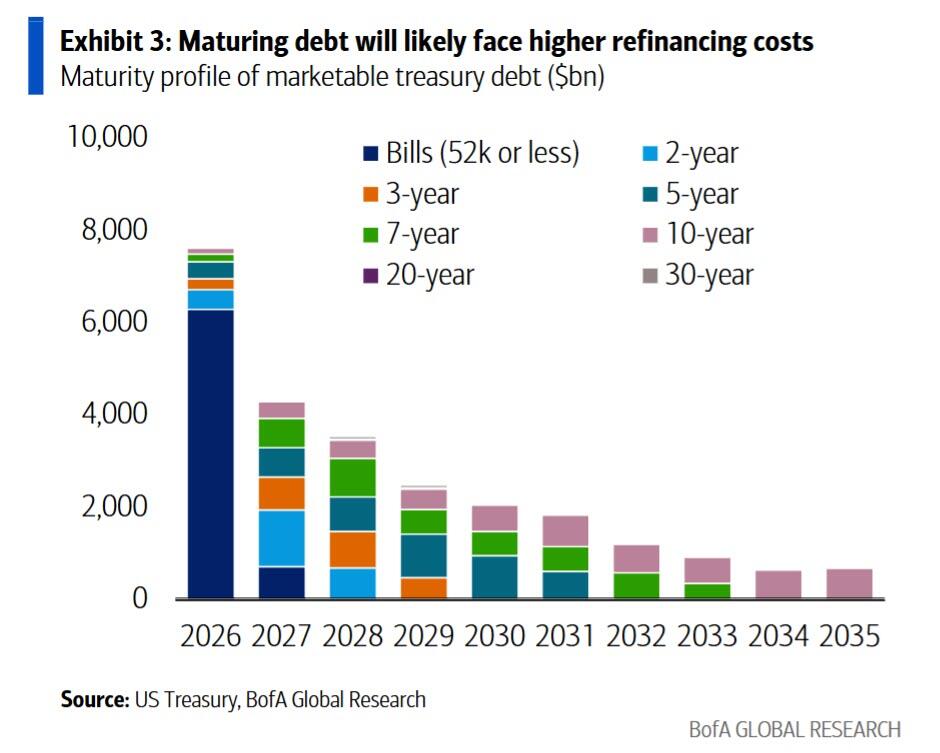
Most importantly, and this is what we started the post with, is that the Treasury’s increased reliance on bills also leaves borrowing costs more sensitive to near-term monetary policy. As Bhave writes, nearly $7 trillion of Treasury bills are currently outstanding, the vast majority of which mature within one year. 

Source: BofA

Assuming the Fed hikes rates by 75bp this year as BofA expects (once this week, and two more times before the latest Fed Hiking cycle ends), BofA concludes that annual interest costs on outstanding T-bills could increase by roughly $50bn or ~15bps of GDP.

It gets worse.

As a reminder of the pernicious nature of compounding debt, in addition to higher refinancing costs on the horizon, BofA warns that a more fundamental concern is the feedback loop between interest rates and debt. Ultimately, debt sustainability depends not only on the level of interest rates, but also on how those rates compare with nominal GDP growth. When nominal growth exceed borrowing costs, debt-to-GDP ratios can stabilize over time. However, as the gap between interest rates and nominal growth narrows, higher debt levels become increasingly difficult to sustain.

The risk is that the self-reinforcing dynamic between interest costs and deficits can further narrow that gap over time.

Meanwhile, there is a feedback loop between higher interest costs and deficits that we must account for. Higher interest costs increase deficits and Treasury borrowing needs, which in turn result in even more interest expense. Increased Treasury issuance can put upward pressure on term premiums as investors demand greater compensation to absorb a larger supply of duration. Higher term premiums raise borrowing costs, which further increase interest expense and deficits, creating a self-reinforcing dynamic.

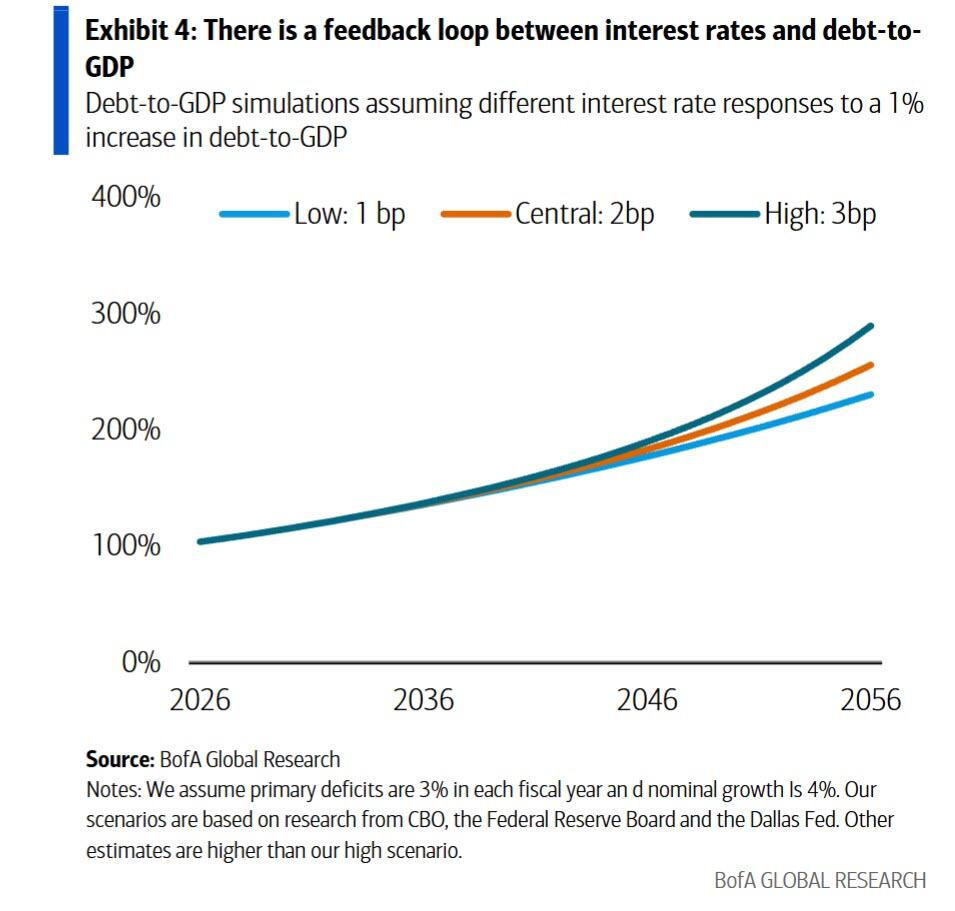
Obviously, the risk from this dynamic is not immediate, which only makes it worse as generations of politicians can sweep it under the rug (dealing with unsustainable spending and debt is not only unpleasant, it is a career killer for politicians), until it becomes to late to deal with it and the problem explodes. Sure enough, this dynamic emerges only gradually as a larger share of the debt stock is refinanced at higher rates and interest expense consumes an increasing share of federal spending. To illustrate this, BofA simulates debt-to-GDP trajectories under three scenarios for how interest rates respond to higher debt.

Source: BofA

In the low, central, and high scenarios, a 1 percentage point increase in the debt-to- GDP ratio raises interest rates by 1bp, 2bp, and 3bp, respectively. While the effects are modest initially, the trajectories diverge meaningfully over longer horizons as higher debt levels lead to higher borrowing costs, which further accelerate debt accumulation.

The composition of deficits matters

The growing share of deficits attributable to interest costs has important implications for both the economy and financial markets. That’s because deficits driven by rising interest expense provide far less support to economic activity than deficits associated with tax relief or government spending, and are far less defensively politically. In addition, they may crowd out both public and private investment by placing sustained upward pressure on long-term interest rates. Over time, they constrain the government’s ability to provide fiscal support during economic downturns, potentially slowing the pace of recovery and resulting in a full-blown fiscal crisis.

For markets, the changing composition of deficits matters because it can lead to greater Treasury issuance without a corresponding boost to economic growth. As a result, it may place additional upward pressure on Treasury supply, term premiums, and ultimately the long end of the yield curve.

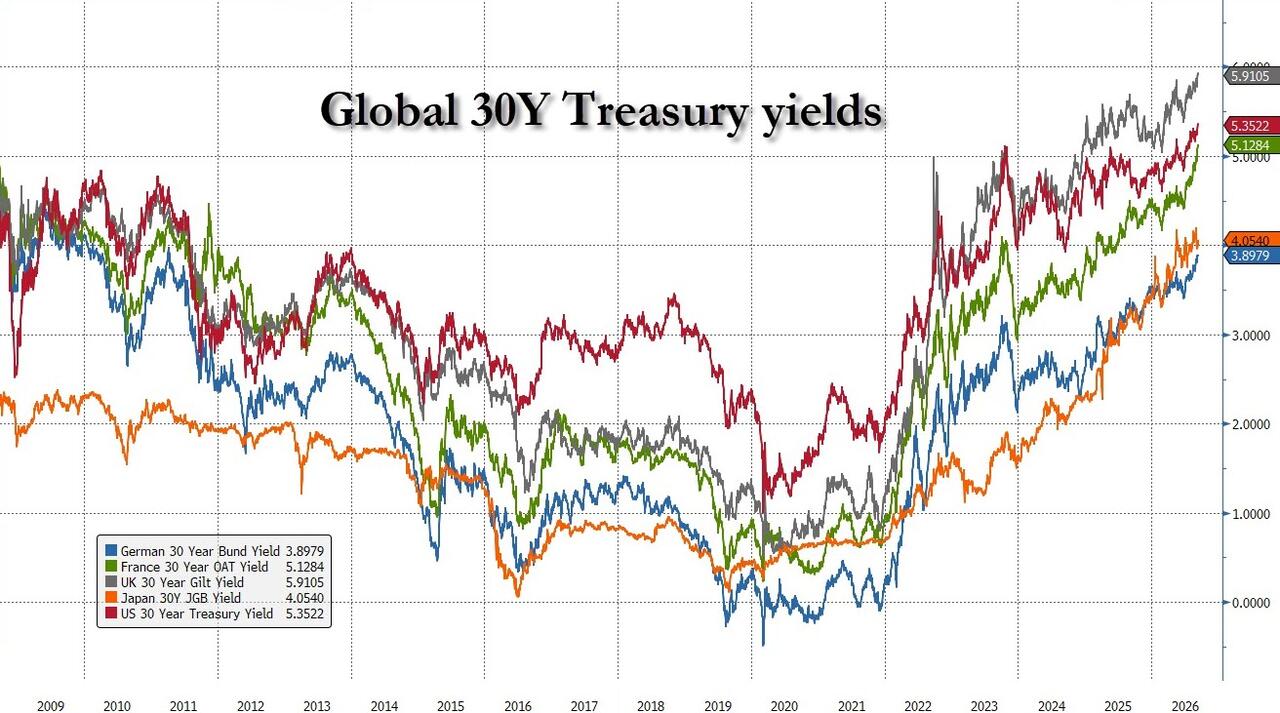
To see this in practice, look no further than interest rates on the long-end of the Treasury curve… but not just in the US – anywhere else too. 

In conclusion, nobody wins from adding another $50 billion of interest cost to the country (except for America’s short-term creditors of course). As Peter Tchir wrote earlier, with interest expense already an issue relative to defense or discretionary spending, a rate hike does not help on that front.

Putting it together, the Academy Securities trader wrote that he finds it “difficult to imagine President Trump liking the idea, even if it helps the longer end of the yield curve, or that stocks have priced it in.”

Of course they haven’t, but stocks remain hypnotized in an AI-bubble, which ironically is kept afloat only thanks to record debt issuance (now that capex is funded largely from new debt), which will come to a crashing halt once Treasury yields spike and the credit market slams shut once. And as always happens, all of these things will take place all at once triggering the next Fed bailout of, well, everything. 

More in the full BofA note available to pro subscribers

Tyler Durden
Mon, 09/14/2026 – 06:55

via ZeroHedge News https://ift.tt/H6epMD8 Tyler Durden

Should Data Centers Go Seasteading?


An illustration of an underwater data center | Illustration: Midjourney

Hating data centers might be misguided, but it’s also ubiquitous, at least in the U.S. And politicians have been capitalizing on this to score populist points by pushing through burdensome regulations. What’s an artificial intelligence company to do?

Go seasteading, possibly.

“Some developers are now exploring the ocean as a new location for AI infrastructure in the hopes that underwater data centers could improve energy use and cooling efficiency while using less fresh water and land area than onshore buildings,” writes University of North Carolina Greensboro management professor Nir Kshetri, who studies the social and environmental effects of emerging technology. He calls under-the-sea data centers “a promising new approach for supporting the growth of AI.”

Underwater data centers would be not technically be “seasteaders“—autonomous entities based far enough offshore that they’re not subject to the rules of any government.

Even if underwater data centers could be based physically far enough from shore that they’re not in anyone’s national waters—not necessarily impossible, but impractical, costly, and a logistical nightmare—they would still be subject to various rules of international waters and would still need cables connecting them to land. They would also be run by tech companies based within an existing country’s borders and subject to that country’s oversight and regulations.

So while building underwater might solve some energy and land-use issues, it wouldn’t solve what are gearing up to be the main barriers to data center construction: political animus and overregulation.

Microsoft has already shown that underwater data centers are not just possible but potentially better than their landlocked counterparts. From Kshetri:

In 2015, Microsoft launched a research project to explore the feasibility, benefits and challenges of underwater data centers. Part of that effort included setting up a waterproof data center on the seafloor near Scotland’s Orkney Islands in 2018. It contained 864 servers and was connected to shore by an underwater cable.

After two years, Microsoft reported that the servers in the underwater data center failed at about one-eighth the rate of servers in comparable land-based data centers. The company is still studying the possible reasons but hypothesizes that in a sealed underwater environment the equipment is less exposed to oxygen, humidity and temperature fluctuations—as well as less jostling from people working to replace broken components.

Microsoft concluded that underwater data centers “are reliable, [are] practical and use energy sustainably.” But it also ended this experiment in 2024 and hasn’t started any more underwater data center since.

“The company didn’t say why,” notes Kshetri, “but others’ analyses suggest the reasons could include regulatory concerns, including the need for environmental permits, as well as a desire for faster upgrades and replacements for the computer equipment inside.”

It seems that people—not technology—could be the biggest obstacle to building more coastal data centers.

And,if that’s the case, we could miss out on a useful and environmental friendly innovation that enables technological progress while still respecting many communities’ desires not to have data centers built in their backyards.

A wind-powered underwater data center in China, launched last year, “uses at least 30% less electricity than traditional data centers, and offshore wind turbines reduce reliance on fossil fuels and cut the data center’s carbon emissions,” Kshetri reports.

Floating data centers like those being tested in Japan and South Korea could also mean less land use and less resource-intense operations.

Moving data centers off shores does create “new concerns about harm to the marine environment,” writes Kshetri. It’s not yet clear “whether the ocean can become AI’s next computing frontier without becoming its next environmental problem.” But with the the right approach, he suggests, underwater data centers could “become sustainable alternatives to traditional data centers.”

Some people are betting big money on that. For instance, Peter Thiel–backed Panthalassa, “a U.S.-based start up betting on ocean waves to power a fleet of floating data centers, announced $140 million in funding” in May, per Fortune magazine.

And federal regulators might not kill this sort of innovation before it takes off. In August, “the Federal Energy Regulatory Commission accepted DeepGreen Western Passage SPV’s filing for a preliminary permit to build a $100 million underwater data center” off the coast of Maine, reports The Maine Monitor. “DeepGreen applied for the 48-month preliminary permit in February to conduct engineering and environmental studies required to secure funding and launch the project. This is not a permit for construction.”

But animosity toward artificial intelligence could still stave off such experiments.

In Maine, DeepGreen’s “application drew an almost immediate response from residents and Passamaquoddy officials, who strongly oppose the development, and prompted two citizen-initiated petitions designed to halt the proposal,” notes the Monitor. “Earlier this month, the city council voted unanimously to enact a 180‑day moratorium, giving city officials time to review and possibly amend local zoning ordinances.”


More Sex & Tech

• Anthropic reports that it “disrupted” people in Yemen trying to use Claude to develop guided weapons. “We do not have evidence the actors succeeded in fielding an operational device; but they did test-fire a guided rocket,” Anthropic reports. “This field test appears to have failed: within hours, the actors returned to Claude to work out why it failed.” It also reportedly discovered “three Iranian state-aligned accounts that were using Claude to set up influence operations campaigns,” including “planning and prepping content to support what they called a ‘soft war’ or ‘cognitive warfare’ program.”
“planning and prepping content to support what they called a ‘soft war’ or ‘cognitive warfare’ program.”

• A California woman was arrested after repeatedly driving by a multi-racial family and accusing the man of trafficking his daughter.

• The “government mandated girlfriend” meme is back.

• Why is Apple bringing back flip phones?

The post Should Data Centers Go Seasteading? appeared first on Reason Magazine.

from Latest – Reason Magazine https://ift.tt/85klXH2
via IFTTT